- Author: Raymond
- Category: Life Insurance in Kenya
Is Life Insurance a Will in Kenya? Why You Need Both
Is life insurance a will in Kenya? Learn the difference between a will, life insurance beneficiaries and estate planning, and why your family may need both.
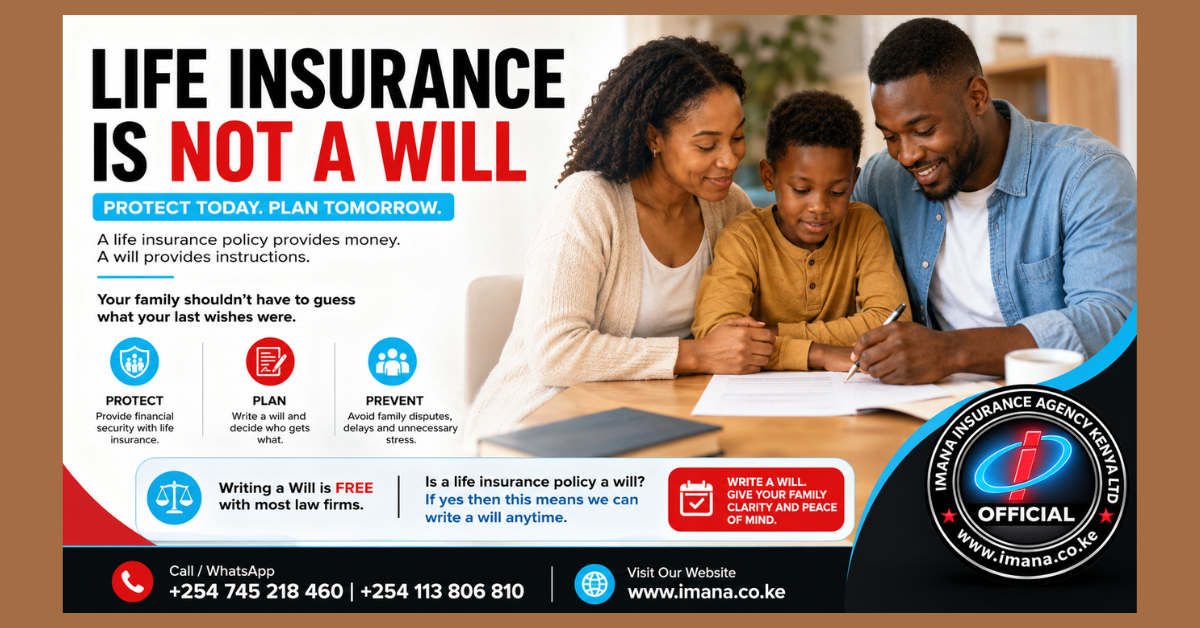
Your family should never have to sit around after your death trying to guess what you wanted.
Who should receive the house? Who takes over the business? What happens to the family vehicle? Who should manage property left for young children? Who receives your life insurance benefits?
These are difficult enough questions when a family is grieving. Leaving them unanswered can create confusion, disagreements and lengthy succession disputes.
That is why writing a will and having adequate life insurance are two important parts of financial and estate planning.
But this raises a common question:
Is a life insurance policy the same thing as a will?
The simple answer is no.
A life insurance policy can provide financial protection to your nominated beneficiaries when you die, while a will provides broader instructions about how you want your estate handled after your death.
Ideally, many people should consider having both.
What Is a Will?
A will is a legal declaration of how you want your property and estate dealt with after your death.
In Kenya, the Law of Succession Act governs wills and the administration of deceased persons' estates. Section 5 provides for the capacity to make a will, including the requirement that the person making it be of sound mind and not a minor.
A properly prepared will can provide instructions concerning assets such as your home, land, vehicles, investments, shares, money, personal belongings and business interests.
It can also identify the person or persons you want to administer your estate.
Without a valid will, your property does not simply get distributed according to informal conversations you may have had with relatives. The estate may instead have to be administered according to Kenya's succession laws.
This is why statements such as "My family already knows what I want" can be dangerous.
Knowing your wishes and having legally recognised instructions are two different things.
Is Life Insurance a Will?
No. A life insurance policy is not a will.
Life insurance is a contract between the policyholder and an insurance company. Depending on the type and terms of the policy, the insurer agrees to pay specified benefits following the occurrence of the insured event, such as the death of the insured person.
Kenya's Insurance Act specifically provides for nomination in relation to life assurance policies. A holder of a life assurance policy on their own life may nominate a person or persons to receive policy money, subject to the provisions of the Act.
That nomination is important, but it does not turn your life insurance policy into a will.
Your life insurance nomination is primarily concerned with the benefits payable under that particular insurance policy.
Your will can deal with the much wider question of what should happen to your estate.
Think of it this way:
Life insurance provides financial protection. A will provides instructions.
Both can form part of a strong estate plan, but they perform different functions.
What Does a Life Insurance Beneficiary or Nominee Mean?
When you take life insurance, you may be asked to nominate the person or people who should receive the policy benefits following your death.
Depending on the insurer and the policy, these could include your spouse, children or other persons you wish to provide for.
Importantly, the Insurance Act allows nomination when the policy is taken out or later before it matures. The Act also contains provisions dealing with the registration, cancellation and alteration of nominations.
This means you should not simply nominate someone when taking your policy and then forget about it for the next 20 years.
Life changes.
You may marry.
You may have children.
You may divorce or remarry.
A beneficiary may die.
Your financial responsibilities may change.
Your business may grow.
Your dependants may become financially independent.
Your estate planning documents and insurance nominations should therefore be reviewed periodically and after major life events.
Why a Life Insurance Policy Cannot Replace Your Will
Imagine you have a KSh 10 million life insurance policy and nominate your spouse and children as beneficiaries.
That nomination may provide instructions concerning the benefits payable under that policy.
But suppose you also own:
A house in Nairobi.
A parcel of land.
Two vehicles.
Shares in several companies.
A family business.
Money in different accounts.
Investment property.
Personal possessions with significant financial or sentimental value.
Your life insurance nomination does not automatically provide comprehensive instructions for distributing all those assets.
That is where a properly prepared will becomes important.
A will can set out your intentions regarding the wider estate and identify who should administer it.
What Makes a Written Will Valid in Kenya?
Simply writing your wishes on a piece of paper and putting it in a drawer is not something you should assume will automatically create an effective written will.
Section 11 of Kenya's Law of Succession Act sets out formal requirements for written wills. Among other requirements, the testator must sign or affix their mark—or have another person sign in their presence and at their direction—and the will must be attested by two or more competent witnesses.
Kenyan courts continue to apply these statutory requirements when determining whether purported wills are valid. For example, a 2026 High Court decision reiterated the Section 11 requirements relating to execution and attestation.
This is one reason professional legal assistance can be valuable, particularly where the estate involves businesses, several properties, blended families, minor children or potentially competing beneficiaries.
Can You Write a Will at Any Time?
Generally, yes.
You do not have to wait until you are elderly, sick or extremely wealthy before thinking about a will.
Under Kenya's succession law, a person who has attained adulthood and has the required mental capacity can make a will.
In fact, waiting until a medical crisis occurs can create unnecessary complications.
Estate planning is better approached while you are healthy, clear about your wishes and able to organise your financial affairs carefully.
A will is not a document about expecting death.
It is a document about taking responsibility for what happens after you are no longer able to make those decisions yourself.
Is Writing a Will Free in Kenya?
Be careful with the statement:
"Writing a will is free with most law firms."
That should not be presented as a general rule.
Some advocates, organisations, financial institutions or legal programmes may occasionally provide free consultations or particular estate-planning services, but there is no general principle that every law firm—or most law firms—must prepare wills free of charge.
Charges can depend on the advocate, complexity of the estate and work required.
What matters more is ensuring that your will complies with Kenyan law and accurately reflects your intentions.
A badly drafted "free" will that creates ambiguity can ultimately cost a family far more in disputes than obtaining proper professional advice would have cost.
What Happens If You Die Without a Will in Kenya?
A person who dies without leaving a valid will is commonly described as having died intestate.
In that situation, distribution and administration of the estate are governed by the applicable provisions of the Law of Succession Act rather than simply by undocumented personal wishes. Kenya's Law of Succession Act is the principal legislation dealing with testamentary and intestate succession and the administration of deceased persons' estates. (Kenya Law)
This does not necessarily mean your family will receive nothing.
It means you have given up much of the opportunity to personally specify how your estate should be handled through a valid will.
That distinction matters.
Why Families Need Both Life Insurance and a Will
A will can say who should receive your property.
But a will does not magically create money.
That is where life insurance can become incredibly important.
Imagine a parent leaves behind a house, land and business interests but very little immediately available cash.
The surviving family may still face school fees, rent or mortgage payments, food, medical expenses, debts, funeral expenses and everyday living costs.
Life insurance can provide financial protection during that transition.
The will deals with your estate and instructions.
Life insurance can provide liquidity and financial support.
Put together, they can create a much stronger financial safety net.
Life Insurance Is Especially Important When People Depend on Your Income
If your death would create an immediate financial problem for another person, life insurance deserves serious consideration.
This is particularly relevant for parents with young children, married couples, homeowners with loans, business owners, people supporting ageing parents, professionals with financial dependants and families relying heavily on one primary income.
Ask yourself one uncomfortable but important question:
If my income disappeared tonight, how long would my family remain financially stable?
A month?
Six months?
A year?
That question often tells you more about the need for life insurance than your age does.
Don't Forget to Review Your Beneficiaries
Taking life insurance is only the beginning.
Your beneficiary or nomination information should remain current.
Review it after major events such as marriage, divorce, the birth or adoption of a child, death of a beneficiary, major business changes or significant changes in your financial responsibilities.
You should also ensure trusted family members know that relevant financial and estate-planning documents exist and where appropriate documentation can be found.
A life insurance policy nobody knows exists can create unnecessary difficulties at exactly the wrong time.
Should Your Will and Life Insurance Policy Name the Same People?
Not necessarily.
Your estate plan depends on your circumstances.
You might want certain property to go to one beneficiary while using life insurance to provide financial support to another.
For example, you could decide that a business should pass to a child who already works in the company while insurance proceeds provide financial protection for other dependants.
However, estate planning can become legally and financially complex. Where significant assets, businesses, trusts, minor children, multiple dependants or potentially conflicting instructions are involved, professional legal and financial advice is highly advisable.
Your insurance adviser can guide you on the insurance side.
A qualified advocate can advise you on the will and succession side.
The two should complement each other.
Can You Change Your Will or Life Insurance Nomination Later?
Your estate plan is not something that should be written once and forgotten forever.
Circumstances change, and both wills and insurance arrangements may need to be reviewed.
Kenya's Insurance Act expressly provides mechanisms concerning nomination, cancellation and changes to nominations under life assurance policies.
Changes to wills must also be handled carefully so that they comply with succession law.
Rather than making informal handwritten amendments to important documents, seek appropriate professional advice whenever you want to make significant changes.
A Simple Estate-Planning Conversation Every Family Should Have
Estate planning does not have to begin with lawyers, complicated documents and millions of shillings.
It can begin with a family conversation.
Consider these questions:
- What assets do I own?
- What debts and financial obligations would remain if I died?
- Who currently depends on my income?
- Do I have adequate life insurance?
- Are my insurance beneficiaries or nominees current?
- Do I have a valid will?
- Who would manage my estate?
- Where are my important documents kept?
- Has my estate plan been reviewed after major changes in my life?
Answering those questions can reveal gaps you did not realise existed.
Life Insurance and Wills Are About Protecting the People You Leave Behind
Nobody enjoys thinking about their own death.
But refusing to plan does not prevent death. It simply transfers difficult decisions to the people left behind.
Your family should not have to guess what your last wishes were.
They should not have to search through drawers wondering whether you had insurance.
They should not have to argue over property because everybody remembers a different version of what you supposedly said.
And they should not suddenly discover that the family breadwinner had no financial protection in place.
Write down your wishes properly. Protect your income with appropriate life insurance. Keep your beneficiaries updated. Review your plan as your life changes.
A will and a life insurance policy are not the same thing.
They are two different tools solving two different problems.
A will tells your family what you wanted done with your estate.
Life insurance helps provide the money your loved ones may need when you are no longer there to provide it.
For many families, the strongest approach is not choosing between the two.
It is having both.
Looking for Life Insurance in Kenya?
Imana Insurance Agency Kenya Ltd can help individuals, families and businesses compare suitable life insurance options from insurance providers and understand important considerations such as benefits, premiums, policy terms and beneficiary nominations.
Insurance guidance should, however, not be treated as a substitute for legal advice when preparing a will. For succession and estate-planning matters, consider consulting a qualified advocate.
Protect the people you love today, while you still have the opportunity to make the decisions yourself.
Disclaimer: This article is intended for general educational information and should not be interpreted as legal advice. Succession and insurance arrangements vary depending on individual circumstances. Consult a qualified advocate for advice about wills and succession, and a licensed insurance professional for insurance advice.