- Author: Raymond
- Category: Corporate & SME Insurance in Kenya
Corporate Insurance Kenya | WIBA, GPA, Group Medical & More
Explore Corporate Insurance in Kenya, including WIBA, GPA, Group Life, Group Medical, Professional Indemnity, Public Liability, Marine, Fire, Business Interruption, Cyber and Contractors All Risks Insurance.
What Is Corporate Insurance in Kenya?
Corporate Insurance is not one insurance policy.
It is a structured combination of insurance covers designed to protect an organisation against risks involving:
- Employees
- Property
- Customers
- Professional services
- Cyber systems
- Machinery
- Cargo
- Construction projects
- Legal liability
- Business interruption
A company may therefore need several insurance policies working together rather than relying on a single general business policy.
At Imana Insurance Agency Kenya Ltd, corporate insurance is approached from a risk-management perspective: understand what the organisation does, identify the financial exposures, compare suitable insurance quotations and structure protection around the business rather than simply buying isolated policies.
Imana currently positions corporate insurance, WIBA, Professional Indemnity, commercial packages and other business solutions among its core offerings for SMEs and larger organisations in Kenya. (Imana)
The purpose of Corporate Insurance is not to insure everything. It is to identify the risks that could seriously disrupt the organisation and transfer appropriate risks to insurers.
Why Is Corporate Insurance Important?
A business may own valuable assets and still face risks that do not involve physical property.
For example:
- An employee may be injured at work.
- A customer may suffer an accident at the premises.
- A professional mistake may cause a client financial loss.
- A fire may close the business for several months.
- A cyberattack may interrupt operations.
- Imported stock may be damaged in transit.
- A construction project may suffer accidental damage.
Each of these exposures requires a different insurance response.
The right corporate insurance programme should therefore consider:
- People
- Property
- Liability
- Income
- Technology
- Transport and cargo
- Projects
- Contractual obligations
1. WIBA Insurance in Kenya
WIBA Insurance protects an employer against qualifying liabilities arising from work-related injuries, accidents and occupational diseases affecting employees.
Under Kenya’s Work Injury Benefits Act, an employer can be liable to compensate an employee for qualifying occupational injuries, and workplace accidents must be notified through the applicable statutory process. (Kenya Law)
WIBA may therefore be relevant to virtually any organisation employing people.
This includes:
- Offices
- Schools
- Hospitals
- Hotels
- Manufacturers
- Contractors
- Restaurants
- Security companies
- Transport businesses
- NGOs
- Professional firms
- Retail businesses
Information required for a WIBA quotation
An insurer may request:
- Number of employees
- Employee occupations
- Annual gross payroll
- Work locations
- Nature of business
- Previous claims
- Policy period
Higher-risk occupations may attract different rates from office-based employees.
For example, the risk presented by:
- An accountant
- A construction worker
- A machine operator
- A driver
is not identical.
Imana publishes dedicated WIBA guidance and identifies WIBA as one of its core corporate insurance solutions. (Imana)
Learn more:
https://imana.co.ke/insurance/wiba-insurance
2. Group Personal Accident Insurance
Group Personal Accident Insurance, commonly called GPA, provides defined benefits following accidental injury or death affecting insured members of a group.
While WIBA focuses on qualifying work-related injuries, GPA can potentially provide broader accident protection depending on the policy structure.
A GPA policy may provide benefits for:
- Accidental death
- Permanent disability
- Temporary disability
- Accidental medical expenses
- Funeral expenses
- Emergency evacuation
Some employers arrange GPA on a 24-hour basis, providing accident protection beyond ordinary working hours.
Why employers combine WIBA and GPA
These two covers can complement each other.
WIBA
Primarily addresses the employer's statutory work-injury exposure.
GPA
Can provide broader defined accident benefits to employees.
A corporate insurance programme may therefore contain both policies rather than treating one as a replacement for the other.
3. Group Life Insurance
Group Life Insurance provides financial protection to employees' nominated beneficiaries where an insured employee dies during the policy period, subject to the terms of the policy.
The benefit may be expressed as:
- A fixed amount
- A multiple of annual salary
- A graded benefit based on employee category
For example, a company may arrange a Group Life benefit equivalent to:
- One year's salary
- Two years' salary
- Three years' salary
depending on the programme design.
Why Group Life matters
The death of an employee can create significant financial pressure on their dependants.
The benefit may help surviving family members meet:
- Rent or mortgage expenses
- School fees
- Household expenses
- Funeral costs
- Outstanding debts
- Immediate living expenses
Group Life can also strengthen an organisation's employee-benefits package.
4. Group Medical Insurance
Group Medical Insurance helps employers provide healthcare protection to employees and, where selected, their dependants.
Benefits may include:
- Inpatient treatment
- Outpatient treatment
- Maternity
- Dental
- Optical
- Chronic illness
- Cancer treatment
- Renal treatment
- Emergency evacuation
- Last Expense
Imana offers health and medical insurance solutions for individuals, families and corporate clients. (Imana)
What employers should compare
Do not compare Group Medical quotations using premium alone.
Review:
- Inpatient limit
- Outpatient limit
- Hospital network
- Co-payment
- Maternity limit
- Chronic-condition benefits
- Cancer and renal limits
- Dental and optical benefits
- Waiting periods
- Member age structure
- Claims experience
Two quotations with the same headline inpatient limit may provide very different overall protection.
5. Professional Indemnity Insurance
Professional Indemnity Insurance protects professionals and businesses against eligible claims alleging that professional advice, services, errors or omissions caused a client financial loss.
It may be relevant to:
- Lawyers
- Accountants
- Auditors
- Architects
- Engineers
- Consultants
- Insurance intermediaries
- Doctors
- Medical facilities
- Surveyors
- Valuers
- Technology companies
- Project managers
Imana provides a dedicated Professional Indemnity Insurance quotation service in Kenya. (Imana)
Claims may involve allegations of:
- Professional negligence
- Incorrect advice
- Errors
- Omissions
- Failure to perform agreed professional duties
- Breach of professional duty
The policy should accurately describe the services the company actually provides.
Important considerations include:
- Limit of indemnity
- Policy excess
- Retroactive date
- Territorial jurisdiction
- Defence costs
- Exclusions
Learn more:
https://imana.co.ke/professional-indemnity
6. Public Liability Insurance
Public Liability Insurance protects a business against eligible legal claims arising where a member of the public or another third party suffers accidental bodily injury or property damage connected to the insured's operations.
Examples include:
- A customer slipping in a supermarket.
- A visitor being injured at an office.
- Water from a business premises damaging neighbouring property.
- Equipment accidentally damaging third-party property.
- An event attendee suffering an injury.
Public Liability is particularly relevant to businesses that regularly interact with:
- Customers
- Suppliers
- Contractors
- Visitors
- Members of the public
It should not be confused with Professional Indemnity.
Public Liability
Deals mainly with bodily injury and property damage.
Professional Indemnity
Deals primarily with financial loss arising from professional services.
Some businesses require both.
7. Marine Insurance
Marine Insurance protects cargo and other insured interests during transportation, depending on the policy selected.
Imana offers Marine Insurance solutions for cargo and vessels and provides marine insurance quotations in Kenya. (Imana)
Corporate clients may require Marine Insurance for:
- Imports
- Exports
- Machinery
- Raw materials
- Finished goods
- Electronics
- Commercial stock
- Project equipment
Marine Cargo Insurance
Marine Cargo may protect goods while moving by:
- Sea
- Air
- Road
- Rail
depending on the territorial and transit conditions.
Marine Open Cover
Companies importing or exporting goods regularly may consider an annual Marine Open Cover rather than arranging a separate policy for every shipment.
This can simplify:
- Insurance declarations
- Certificate issuance
- Cargo administration
- Regular shipments
Learn more:
https://imana.co.ke/marine-insurance
8. Fire and Allied Perils Insurance
Fire can cause more than physical damage to a building.
It can destroy:
- Stock
- Machinery
- Furniture
- Computers
- Raw materials
- Finished goods
- Documents
Fire and Allied Perils Insurance may protect declared property against risks such as:
- Fire
- Lightning
- Explosion
- Storm
- Flood
- Earthquake
- Impact
- Burst pipes
- Malicious damage
depending on the policy.
The business should maintain accurate sums insured for:
- Buildings
- Contents
- Stock
- Machinery
- Equipment
Underinsurance may significantly affect a claim.
9. Business Interruption Insurance
A business can survive the physical damage from a fire yet fail financially because it cannot operate afterwards.
This is where Business Interruption Insurance becomes important.
Property Insurance pays for eligible physical damage.
Business Interruption may address the financial consequences of that damage.
Depending on the policy, it may protect:
- Gross profit
- Continuing expenses
- Rent
- Salaries
- Additional operating expenses
- Lost income during restoration
Example
A warehouse suffers a major fire.
Fire Insurance may pay for:
- Building repairs
- Damaged equipment
- Insured stock
But the company may remain closed for six months.
During that period it could still have:
- Salaries
- Rent
- Loan obligations
- Utilities
- Other fixed costs
Business Interruption Insurance is designed to address that second layer of risk.
Imana's business insurance offerings include Consequential Loss, another commonly used term for Business Interruption protection. (Imana)
10. Cyber Insurance
Modern businesses increasingly depend on:
- Cloud platforms
- Mobile money
- Online banking
- Customer databases
- Websites
- Digital payment systems
- Remote working
This creates new risks.
Cyber Insurance may provide eligible protection following incidents such as:
- Data breaches
- Ransomware
- Cyber extortion
- System interruption
- Business-email compromise
- Privacy claims
- Data restoration
- Incident-response expenses
Cyber Insurance should complement—not replace—good cybersecurity practices.
Businesses should also maintain:
- Multi-factor authentication
- Secure backups
- Employee cybersecurity training
- Access controls
- Updated software
- Incident-response procedures
A small business can still suffer a major cyber loss. Cyber risk is not limited to banks or multinational corporations.
11. Contractors All Risks Insurance
Contractors All Risks Insurance, commonly called CAR Insurance, is designed for construction projects.
It may protect against:
- Accidental damage to contract works
- Construction materials
- Temporary works
- Third-party property damage
- Third-party bodily injury
depending on the policy structure.
It may be required for:
- Commercial buildings
- Residential developments
- Roads
- Warehouses
- Schools
- Hospitals
- Industrial projects
- Civil works
Information required for a CAR quotation
An insurer may request:
- Contract value
- Project description
- Project location
- Construction period
- Bill of quantities
- Contractor experience
- Principal or employer details
- Third-party liability limit
- Project drawings
- Claims history
A construction project may also require:
- WIBA
- Public Liability
- Professional Indemnity
- Contractors' Plant and Machinery
- Performance Bond
- Advance Payment Bond
- Marine Cargo
A single Contractors All Risks policy should therefore not automatically be assumed to cover every project exposure.
How These Corporate Insurance Covers Work Together
The most effective corporate insurance programmes combine several covers according to the business's actual risk profile.
Example: Professional consultancy
A consultancy may require:
- Professional Indemnity
- Cyber Insurance
- WIBA
- Group Medical
- Group Life
- Office Property Insurance
- Public Liability
Example: Manufacturing company
A manufacturer may require:
- WIBA
- GPA
- Group Medical
- Fire and Allied Perils
- Business Interruption
- Machinery Breakdown
- Product Liability
- Marine Cargo
- Cyber Insurance
Example: Construction company
A contractor may require:
- Contractors All Risks
- WIBA
- GPA
- Public Liability
- Contractors' Plant and Machinery
- Professional Indemnity
- Motor Fleet Insurance
- Bid and Performance Bonds
Example: Import and distribution business
An importer may require:
- Marine Cargo
- Fire Insurance
- Business Interruption
- Goods in Transit
- Commercial Motor
- Public Liability
- WIBA
- Cyber Insurance
Corporate Insurance works best as a coordinated programme rather than a collection of unrelated policies.
How to Build a Corporate Insurance Programme in Kenya
Step 1: Identify the organisation's assets
List:
- Buildings
- Machinery
- Vehicles
- Stock
- Computers
- Equipment
- Cargo
Step 2: Identify people risks
Consider:
- Number of employees
- Occupations
- Payroll
- Dependants
- Employee-benefit expectations
Step 3: Identify liability exposures
Ask:
- Can customers be injured?
- Can your product cause damage?
- Do you provide professional advice?
- Do you handle customer information?
- Do contractors visit your premises?
Step 4: Identify income risks
Ask:
How long can this business survive if operations stop?
This helps determine whether Business Interruption Insurance is necessary.
Step 5: Identify contractual requirements
Contracts may require:
- Professional Indemnity
- Public Liability
- WIBA
- Contractors All Risks
- Performance Bonds
- Marine Insurance
Step 6: Compare quotations
Compare more than premium.
Review:
- Limits
- Excesses
- Exclusions
- Sublimits
- Territorial scope
- Claims procedures
- Extensions
- Deductibles
- Insurer appetite
Common Corporate Insurance Mistakes
Buying only compulsory insurance
Meeting minimum statutory requirements may leave major business risks uninsured.
Insuring property but not income
A company may replace damaged equipment and still fail because it lost six months of revenue.
Ignoring cyber risk
Any company processing data or payments digitally may face cyber exposure.
Underinsuring buildings and machinery
Old insured values may no longer reflect current replacement costs.
Treating Professional Indemnity and Public Liability as the same policy
They protect fundamentally different exposures.
Failing to update employee payroll
An outdated WIBA payroll can result in incorrect insurance arrangements.
Not declaring new business activities
A business that changes or expands its operations should notify the insurer.
Why Use an Insurance Intermediary for Corporate Insurance?
Corporate Insurance can involve several insurers, policies and renewal dates.
A dedicated intermediary can help:
- Identify risk gaps.
- Prepare underwriting information.
- Obtain quotations.
- Compare insurer terms.
- Explain exclusions.
- Coordinate policy issuance.
- Maintain insurance schedules.
- Support claims.
- Conduct renewal reviews.
Imana describes itself as a digital insurance agency based in Westlands, Nairobi, helping customers source and compare insurance quotations and choose appropriate insurance companies for their risks. (LinkedIn)
How Imana Helps Corporate Clients
Imana Insurance Agency Kenya Ltd helps SMEs, employers, contractors, professional firms and larger organisations structure suitable corporate insurance programmes.
Corporate solutions may include:
- WIBA
- Group Personal Accident
- Group Life
- Group Medical
- Professional Indemnity
- Public Liability
- Marine Insurance
- Fire and Allied Perils
- Business Interruption
- Cyber Insurance
- Contractors All Risks
- Motor Fleet Insurance
- Property Insurance
- Bonds and Guarantees
- Other specialised covers
Imana's public website identifies the agency as a provider of corporate insurance solutions and specialist commercial covers for SMEs and larger organisations. (Imana)
Corporate Insurance in Westlands, Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Imana's website and blog directory confirm its office location at Krishna Centre, Woodvale Grove, Westlands. (Imana)
Useful links
Website:
https://imana.co.ke
Corporate Insurance:
https://imana.co.ke/insurance/corporate-insurance
WIBA Insurance:
https://imana.co.ke/insurance/wiba-insurance
Professional Indemnity:
https://imana.co.ke/professional-indemnity
Marine Insurance:
https://imana.co.ke/marine-insurance
Corporate Quotation:
https://imana.co.ke/corporate-quote
Frequently Asked Questions About Corporate Insurance in Kenya
What is Corporate Insurance?
Corporate Insurance is a combination of insurance policies designed to protect an organisation's employees, assets, liabilities, income and operations.
Does every company need the same insurance covers?
No.
The right programme depends on:
- Business activities
- Employees
- Assets
- Contracts
- Customers
- Locations
- Technology
- Revenue
Is WIBA Insurance important for employers?
Yes. Kenya's Work Injury Benefits framework creates employer responsibilities in relation to qualifying workplace accidents and occupational injuries. (Kenya Law)
Is WIBA the same as GPA?
No.
WIBA addresses qualifying work-related injuries within the statutory framework.
GPA provides defined Personal Accident benefits and can potentially be structured more broadly.
What is the difference between Group Life and Group Medical?
Group Life provides a death benefit.
Group Medical covers eligible healthcare expenses.
Who needs Professional Indemnity?
Businesses and individuals providing professional advice or services should consider it.
Does Fire Insurance cover loss of income?
Not automatically.
Business Interruption or Consequential Loss Insurance may be required to protect eligible lost income following insured physical damage.
Who needs Marine Insurance?
Importers, exporters, manufacturers, traders and other businesses moving valuable goods may require Marine Cargo Insurance.
Is Cyber Insurance only for large companies?
No.
SMEs and professional firms can also suffer serious cyber losses.
Does Contractors All Risks cover employees?
Not necessarily. WIBA or other employee-related protection may still be required.
Can Imana compare Corporate Insurance quotations?
Yes. Imana can help organisations prepare underwriting information, obtain suitable quotations and compare the available policy terms.
The Bottom Line
A strong Corporate Insurance programme should answer one question:
If something serious happens tomorrow, which risks could threaten the survival or financial stability of this organisation?
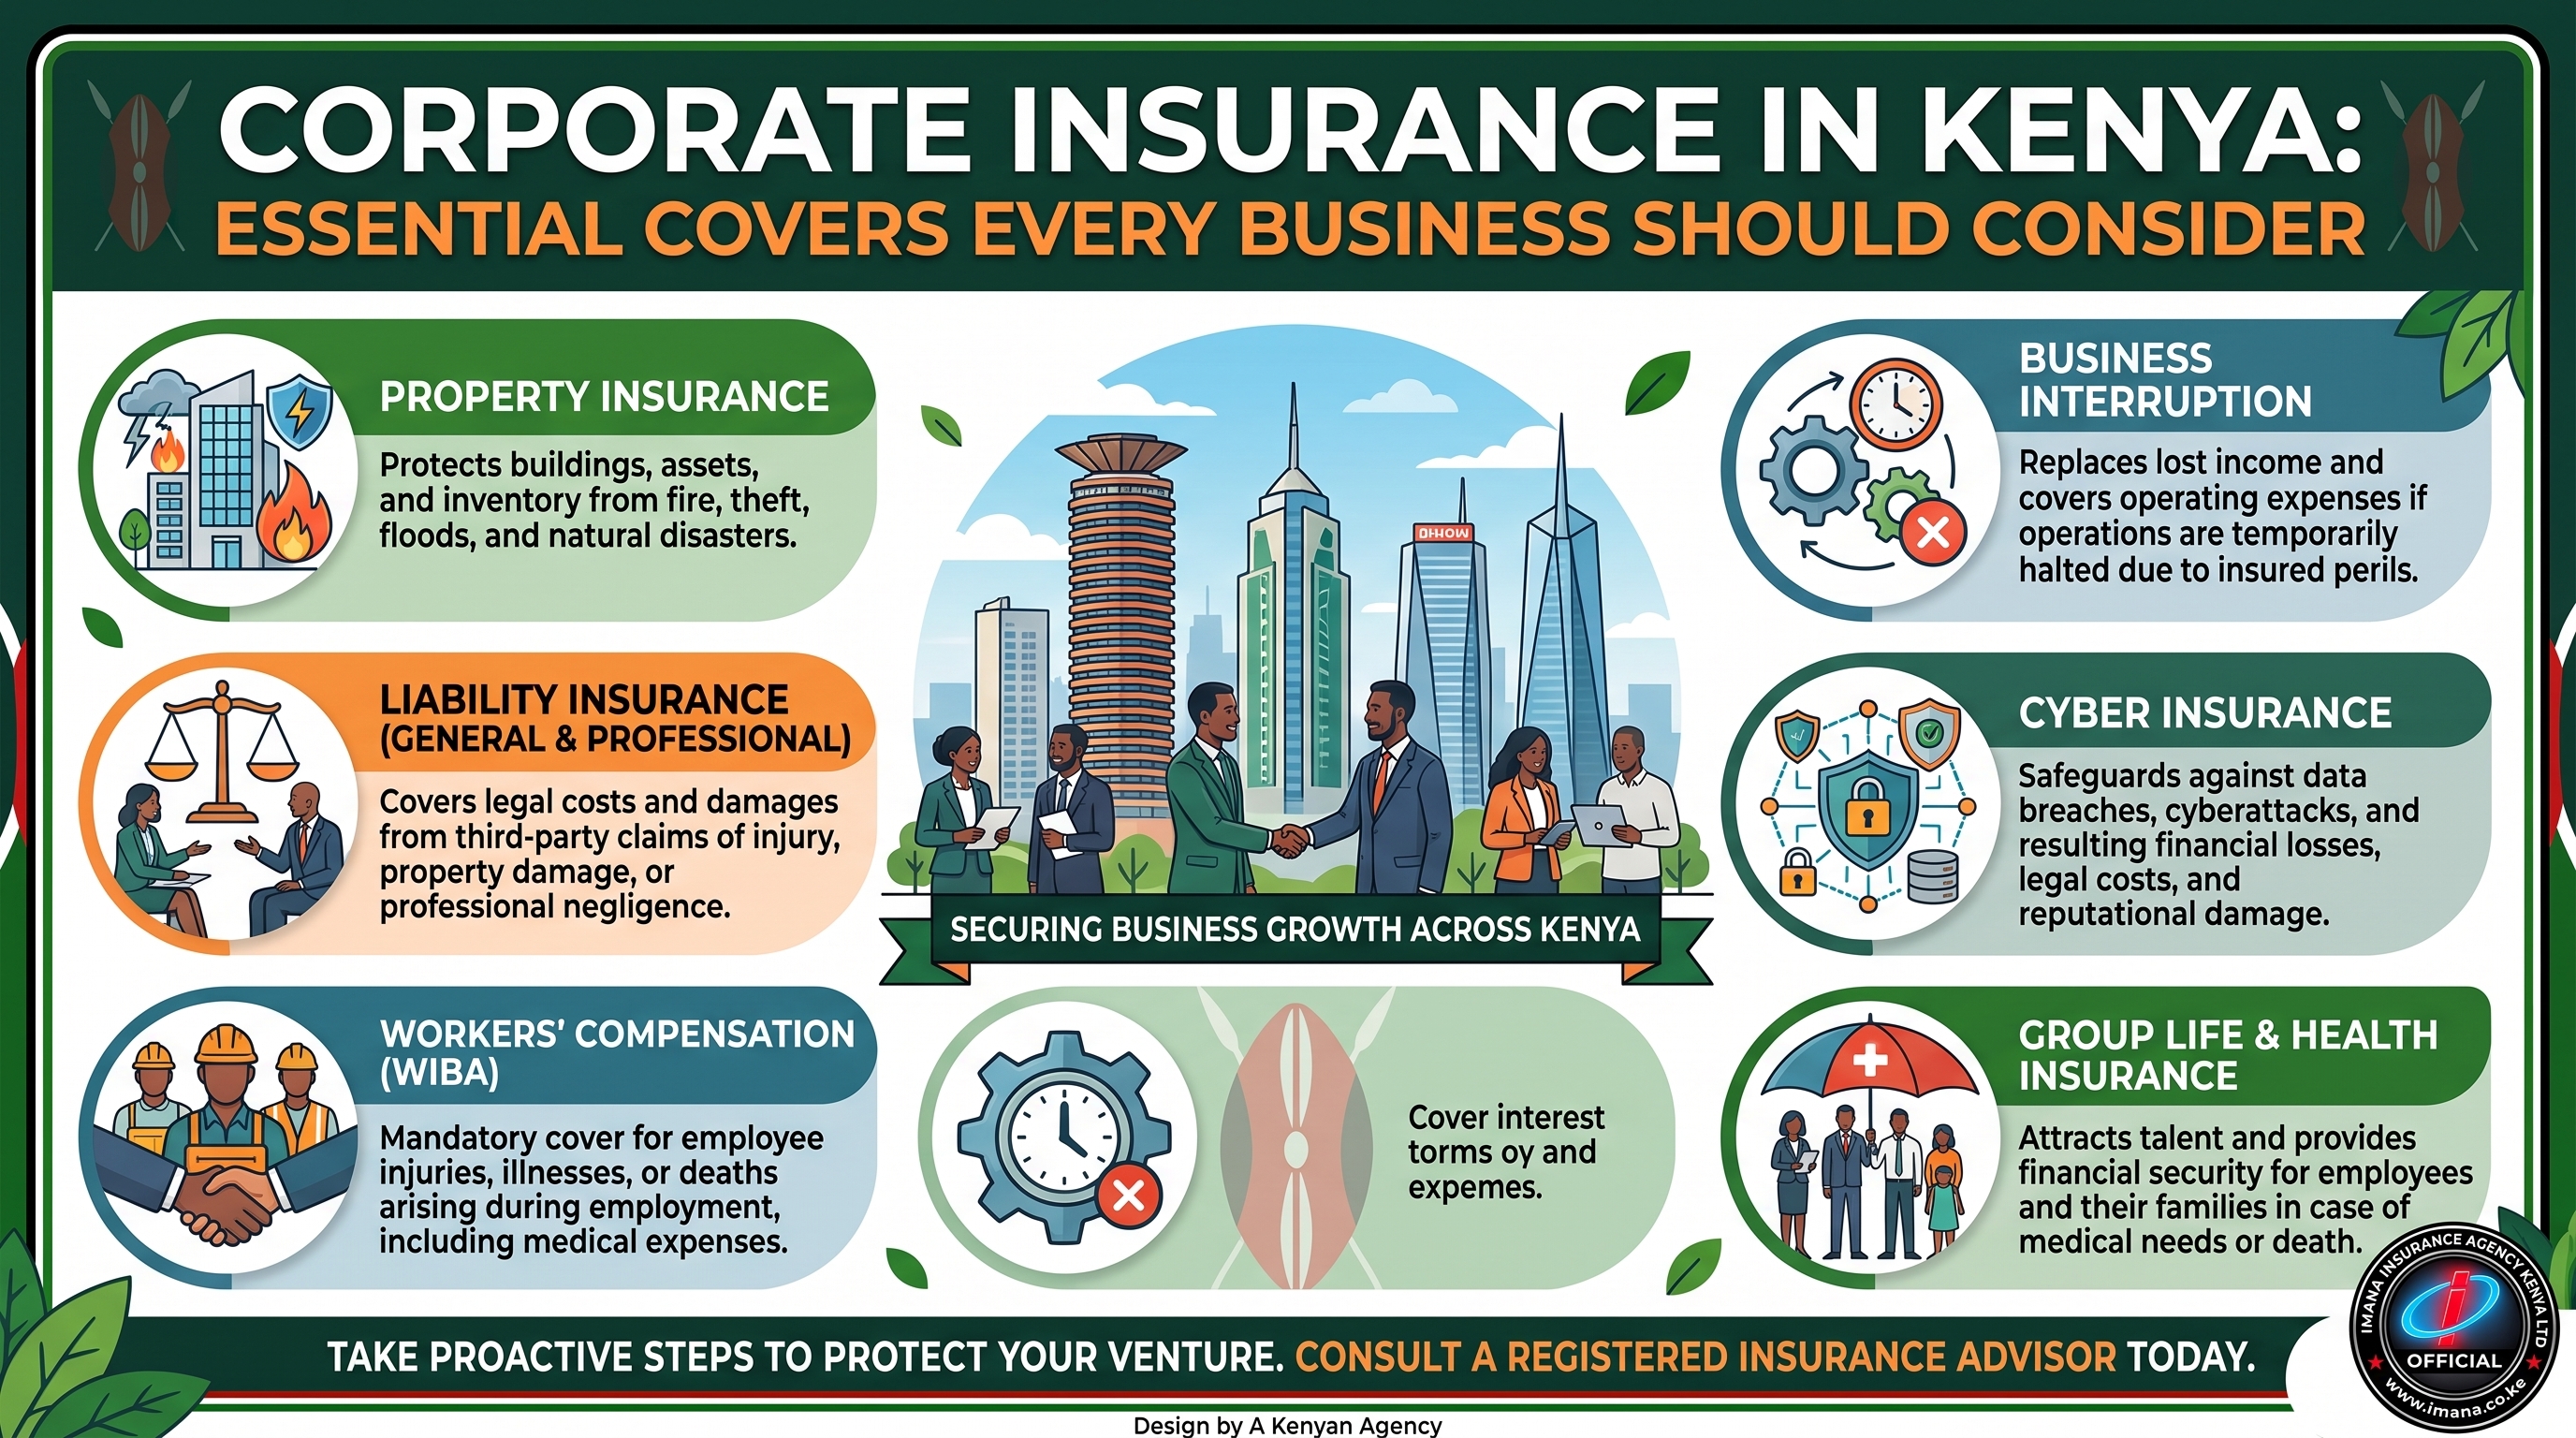
For many Kenyan organisations, the answer may involve a combination of:
- WIBA – employee work injuries
- GPA – broader accident protection
- Group Life – employee death benefits
- Group Medical – employee healthcare
- Professional Indemnity – professional negligence
- Public Liability – third-party injury and property damage
- Marine Insurance – cargo in transit
- Fire Insurance – physical property damage
- Business Interruption – lost income after insured damage
- Cyber Insurance – digital and data risks
- Contractors All Risks – construction projects
No organisation should simply copy another company's insurance programme.
The right approach is:
Identify the risks. Quantify the exposure. Compare the policies. Understand the exclusions. Review the programme regularly.
Contact Imana Insurance Agency Kenya Ltd
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi, Kenya
Website: https://imana.co.ke
Corporate Insurance: https://imana.co.ke/insurance/corporate-insurance
Author: Raymond Momanyi – Founder & CEO, Imana Insurance Agency Kenya Ltd
Protect your people. Protect your assets. Protect your income. Protect the future of the organisation.
Corporate insurance premiums, benefits, limits, excesses and underwriting requirements vary between insurers and businesses. Obtain current written quotations and full policy wording before selecting cover.
Author: Raymond Momanyi – Founder & CEO, Imana Insurance Agency Kenya Ltd