- Author: Raymond
- Category: Insurance Claims
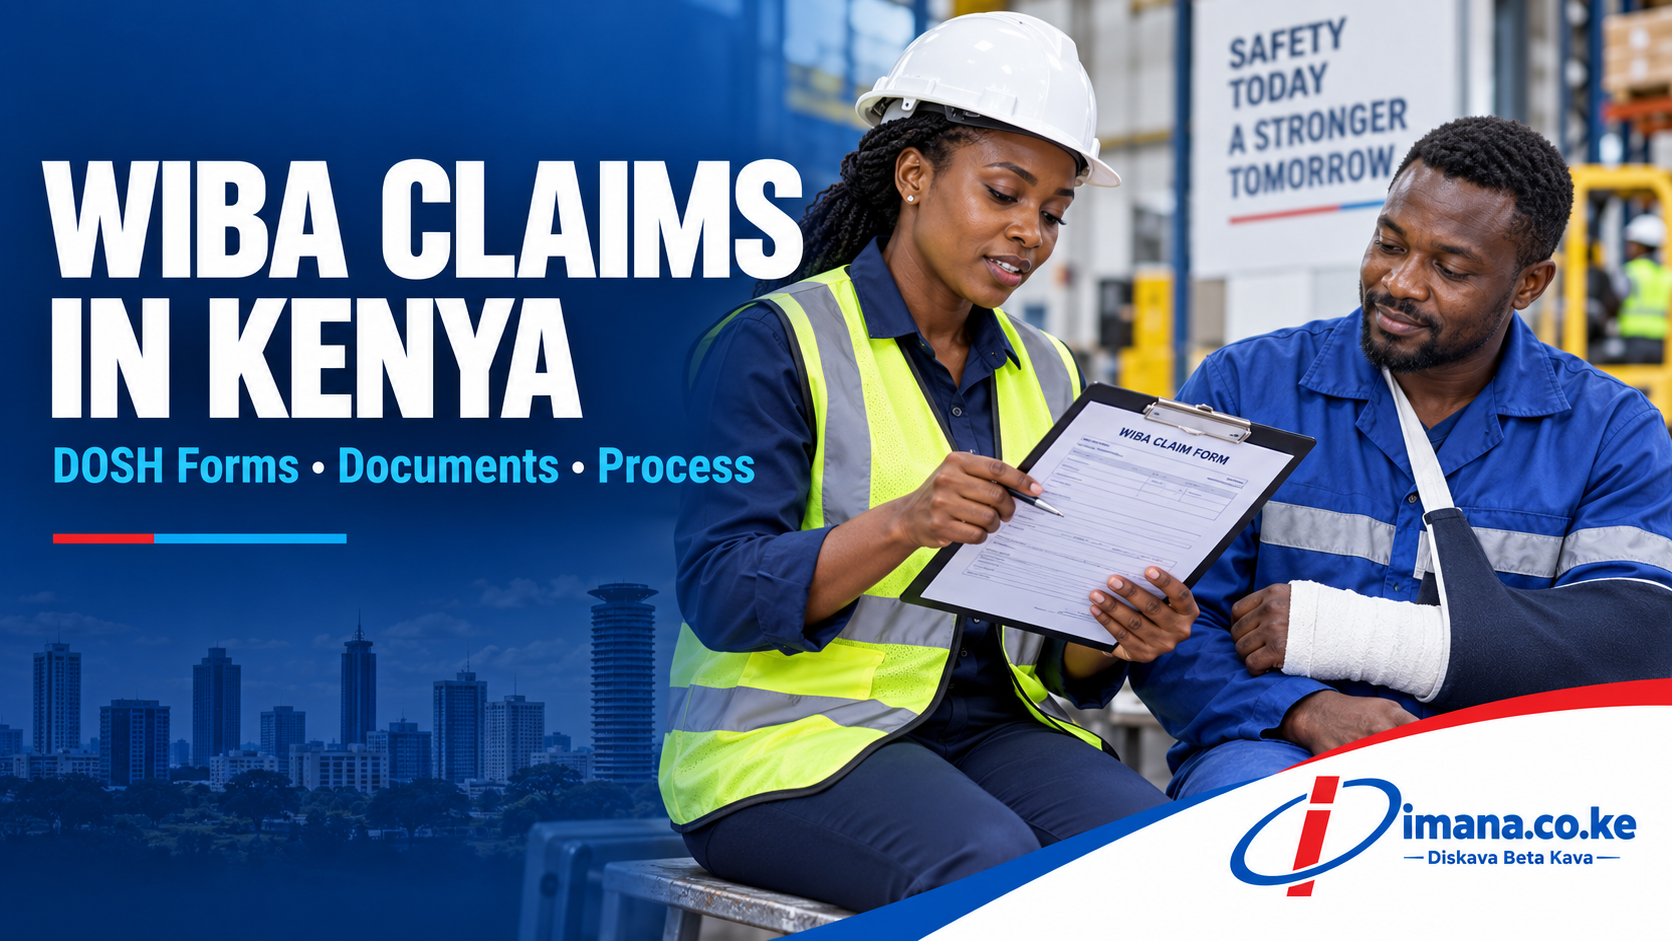
WIBA Claims in Kenya: DOSH Forms, Documents & Process
Learn the WIBA claims process in Kenya, including DOSH 1, medical reports, employer duties, compensation assessment, documents and claim delays.
WIBA Claims Process in Kenya: DOSH Forms, Documents and Timelines
When an employee is injured at work, the first priority is medical care—not paperwork. But once the immediate danger has been addressed, the employer must move quickly.
A delayed accident report, incomplete DOSH form, missing payroll record or unclear medical assessment can turn a straightforward workplace injury into a long and frustrating claim.
This guide explains the WIBA claims process in Kenya, including employer responsibilities, DOSH forms, medical reports, temporary and permanent incapacity, death benefits, supporting documents and the role of the insurer.
Quick answer: After a workplace accident, the employer should arrange immediate medical attention, record the incident, notify the Directorate of Occupational Safety and Health Services using the prescribed DOSH form, inform the WIBA insurer and preserve all medical, employment, payroll and accident evidence.
Imana Insurance Agency Kenya Ltd helps Kenyan employers compare WIBA insurance quotations, understand claim requirements and coordinate communication with insurers.
For assistance, visit the WIBA Insurance page, submit a corporate quotation request or compare business insurance options through ImanaInsurance.com.
What is a WIBA claim?
A WIBA claim is a statutory compensation process arising from an employee’s occupational accident or work-related disease.
The Work Injury Benefits Act, 2007 provides a framework for compensating employees who suffer injury, disablement, occupational disease or death arising out of and in the course of employment.
The Directorate of Occupational Safety and Health Services—commonly known as DOSHS or DOSH—administers the statutory work-injury process. DOSHS describes WIBA as covering work-related injuries and occupational diseases contracted in the course of employment.
WIBA insurance helps an employer finance this statutory exposure, subject to the policy terms. However, purchasing insurance does not remove the employer’s legal obligation to report accidents, maintain employment records, cooperate with investigations and protect employees.
What should an employer do immediately after a workplace accident?
1. Arrange immediate medical attention
The injured employee should receive appropriate first aid and be taken to a suitable medical facility when necessary.
In an emergency, treatment should not be delayed while waiting for:
- A claim number
- A completed DOSH form
- Insurer approval
- A police abstract
- A written referral letter
- Confirmation that the claim will be accepted
The employer should record the name of the hospital or clinic, the treating doctor, the time of admission and the treatment provided.
Where possible, inform the medical facility that the injury occurred at work. This helps ensure that the medical notes clearly record the history and circumstances of the injury.
2. Secure the accident scene
The employer should prevent further injury, isolate dangerous machinery or equipment and preserve the scene where an investigation may be required.
Do not destroy or alter relevant evidence unless this is necessary to rescue an injured person or remove an immediate danger.
Preserve:
- Photographs and videos
- CCTV footage
- Machinery or equipment involved
- Personal protective equipment
- Work permits
- Safety inspection records
- Training records
- Witness statements
- Shift and attendance records
3. Record the incident internally
Enter the accident in the workplace accident register and notify the responsible supervisor, human-resources officer, safety officer or management representative.
Record the basic facts while memories are still fresh:
- Employee’s name and job
- Date, time and location
- Work being performed
- Equipment involved
- Witnesses present
- Immediate injuries observed
- First aid provided
- Medical facility attended
- Steps taken to prevent further harm
4. Notify the WIBA insurer or intermediary
Notify the insurer or Imana Insurance Agency immediately. Do not wait until treatment is completed or permanent incapacity is established.
Early notification allows the insurer to:
- Open a claim file
- Provide the correct document checklist
- Confirm medical-report requirements
- Arrange an investigation where necessary
- Request payroll and employment evidence
- Monitor the employee’s recovery
- Reserve funds for the claim
Insurance notification and statutory reporting to DOSHS are related but separate responsibilities. Informing the insurer does not automatically constitute notification to DOSHS.
How quickly must a workplace accident be reported?
The Ministry of Labour states that fatal accidents should be reported to the appropriate DOSHS county office within 24 hours, while non-fatal accidents should be reported within seven days using the prescribed DOSH 1 form.
An employee should also notify the employer as soon as reasonably possible after an accident.
Employers should not treat seven days as a waiting period. Report immediately once management learns of the occupational injury.
Where the accident involves a road traffic accident, assault, suspected criminal conduct, death or another reportable event, the police may also need to be informed.
What is DOSH 1?
ML/DOSH Form 1 is the official accident notification form used to report an occupational accident or disease to the Director of Occupational Safety and Health Services.
The Ministry of Labour publishes the current DOSH 1 Accident Notification Form through its official forms portal.
The form captures information about:
- The employer
- The injured employee
- Employment and earnings
- Date and location of the accident
- Nature and cause of the accident
- Work being performed
- Injury sustained
- Medical treatment
- Incapacity or disablement
- Dependants where death has occurred
The employer should complete the relevant employer section accurately and submit it through the applicable DOSHS channel.
For a non-fatal injury, the medical practitioner may complete the medical-assessment section after examining or treating the employee. Where treatment is continuing, a final assessment may only be possible after the employee’s condition has stabilised.
Never submit a blank form bearing an employer’s signature or stamp. Keep a complete copy of every form submitted.
What is DOSH 2?
The expression “DOSH 2” is sometimes used loosely in workplace claims discussions to refer to a medical or follow-up assessment document. Employers must be careful because DOSH form numbering has changed over time, and unrelated occupational-safety forms also carry numbers beginning with “DOSH 2”.
Under the current WIBA process, the central accident-notification document is ML/DOSH Form 1. For non-fatal injuries, the medical practitioner records the assessment—including temporary incapacity or permanent disablement—in the applicable medical portion of the prescribed documentation.
Recent Kenyan decisions describe the non-fatal claim process as involving a completed DOSH 1, followed by medical assessment after treatment. The Director may then calculate the benefit and issue a DOSH/WIBA 4 demand for payment.
Therefore, an employer should not download an unofficial “DOSH 2” from an unverified website and assume it is the correct claim form.
Always confirm the exact current form required with:
- The relevant DOSHS county office
- The WIBA insurer
- The appointed claims administrator
- Imana Insurance Agency Kenya Ltd
This protects the employer from submitting an obsolete or unrelated document.
What medical reports are required?
The medical evidence establishes the nature, cause, duration and severity of the employee’s injury or illness.
Depending on the claim, the employer or insurer may require:
- Initial treatment notes
- Outpatient card
- Admission notes
- Discharge summary
- Diagnostic and laboratory reports
- X-rays, CT scans or MRI reports
- Operation notes
- Sick-off sheets
- Prescription records
- Physiotherapy reports
- Specialist reports
- Final medical assessment
- Death certificate and post-mortem report in a fatal claim
The medical history should clearly connect the condition to the reported occupational accident or workplace exposure.
Medical practitioners should avoid assigning final permanent incapacity before the employee’s condition has stabilised. The insurer or Director may request a further examination where the initial evidence is incomplete or inconsistent.
What is the difference between an occupational injury and an occupational illness?
Occupational injury
An occupational injury usually arises from an identifiable workplace event.
Examples include:
- A fall from a ladder
- A machinery injury
- Burns
- An electrical shock
- A vehicle accident during authorised work
- A falling object
- A cut or fracture
- An assault connected with employment
The date, time, location and mechanism of injury can normally be identified.
Occupational illness or disease
An occupational disease may develop gradually because of workplace exposure.
Examples can include:
- Hearing loss caused by prolonged workplace noise
- Respiratory disease linked to dust or chemicals
- Dermatitis caused by occupational substances
- Musculoskeletal conditions associated with repetitive work
- Illness arising from long-term hazardous exposure
An employee and employer may need medical and occupational evidence showing that the disease arose from or was materially connected to the employment.
This may require:
- Employment history
- Exposure records
- Workplace medical-surveillance records
- Occupational hygiene reports
- Specialist medical opinion
- Evidence excluding unrelated causes
A diagnosis alone does not automatically establish occupational causation.
What is temporary incapacity?
Temporary incapacity occurs where an employee is unable to perform normal work for a limited period but is expected to recover.
It may be:
- Temporary total incapacity: The employee cannot work during the certified period.
- Temporary partial incapacity: The employee can perform restricted or lighter duties but cannot carry out their full role.
Evidence may include:
- Sick-off certificates
- Medical reviews
- Treatment notes
- Attendance records
- Payroll records
- Return-to-work documentation
- Light-duty recommendations
Employers should maintain contact with the employee and document any suitable modified duties offered.
A temporary incapacity claim should not be closed merely because the employee has returned to work if treatment is continuing or a permanent impairment remains possible.
What is permanent incapacity?
Permanent incapacity arises where an employee is left with a lasting physical or functional impairment after reaching maximum medical improvement.
The medical practitioner assesses the extent of permanent disablement using the applicable statutory framework. The Director then considers the medical assessment, earnings and WIBA provisions when determining compensation.
Permanent incapacity may be:
- Permanent partial incapacity
- Permanent total incapacity
Examples can include:
- Loss of a finger or limb
- Permanent loss of movement
- Loss of sight or hearing
- Spinal injury
- Permanent neurological impairment
- Serious disfigurement
- Long-term loss of functional capacity
The insurer should not independently invent a disablement percentage. The statutory process and assessment by the Director remain central to the WIBA award.
What happens when an employee dies?
A fatal workplace accident requires urgent action.
The employer should:
- Arrange emergency assistance.
- Notify the police where required.
- Preserve the accident scene.
- Inform DOSHS within the prescribed fatal-accident timeline.
- Notify the WIBA insurer immediately.
- Notify the employee’s next of kin with sensitivity.
- preserve employment and payroll records.
- cooperate with the DOSHS investigation.
- assist with identification of lawful dependants.
A fatal claim may require:
- Completed DOSH 1
- Police abstract or investigation report
- Death certificate
- Post-mortem report
- Burial permit
- Employee identification
- Employment contract
- Payroll and earnings records
- Proof of relationship
- Dependants’ identification documents
- Children’s birth certificates
- Marriage certificate or other dependency evidence
- Chief’s letter where requested
- Letters of administration where applicable
The identification of dependants is a statutory process. Employers should not decide informally who receives the compensation.
Recent WIBA proceedings describe the Director as calculating fatal benefits after identifying the dependants, apportioning the compensation and issuing the applicable demand for payment.
Are funeral expenses covered under WIBA?
WIBA provides for reasonable funeral expenses in a qualifying fatal occupational claim, subject to the applicable statutory framework and policy arrangements.
The employer should retain:
- Funeral invoices
- Transport receipts
- Mortuary receipts
- Burial-related receipts
- Proof of payment
- Details of the person who incurred the expense
Do not promise the family a specific reimbursement before the insurer and DOSHS confirm the applicable benefit and required evidence.
Funeral expenses are separate from compensation payable to the deceased employee’s lawful dependants.
Why are payroll and earnings records important?
WIBA compensation calculations can depend on the employee’s earnings and assessed degree of incapacity.
The employer may be asked for:
- Payslips
- Payroll reports
- Employment contract
- Bank or mobile-money payment records
- Allowance records
- Overtime evidence
- Attendance register
- Statutory deduction records
- Evidence of the employee’s job classification
Recent court proceedings describing DOSHS requirements identify payslips for the month of the accident, the preceding month and the following month among the documents requested for private-sector claims.
Cash-paid and casual employees are not automatically outside the WIBA process. Employers should maintain credible records showing when the employee worked, what duties they performed and how much they earned.
Unclear payroll records can delay the calculation of compensation.
What are the employer’s responsibilities?
An employer’s responsibility does not end after buying a WIBA policy.
Employers should:
- Maintain an active and adequate WIBA policy
- Declare all employees and accurate annual earnings
- Provide a safe working environment
- Train employees appropriately
- Supply suitable protective equipment
- Maintain accident and safety records
- Arrange immediate medical care
- Report occupational accidents and diseases
- Complete DOSH forms accurately
- Preserve accident evidence
- Cooperate with DOSHS and insurer investigations
- Provide medical, payroll and employment documents
- Implement corrective safety measures
- Monitor the employee’s recovery and return to work
The employer remains responsible for compensation where required by law. Insurance is the financial mechanism used to transfer eligible WIBA exposure; it is not a substitute for compliance.
How does the insurer assess a WIBA claim?
After receiving notification, the insurer may:
- Confirm that the policy was active.
- Verify that the injured person was an employee.
- Confirm that the employee was included in the declared workforce.
- Review the employee’s occupation and earnings.
- Examine whether the event arose out of and in the course of employment.
- Review the DOSH notification and medical documents.
- Appoint an investigator where necessary.
- Examine temporary or permanent incapacity evidence.
- Request additional documents.
- Await the Director’s assessment or statutory demand.
- Process payment in accordance with the policy and WIBA decision.
The insurer may investigate the claim, but DOSHS has the statutory role of administering and determining work-injury benefits.
Once an award is determined, DOSH/WIBA Form 4 may be issued as the demand for payment. After payment, DOSHS indicates that a WIBA 7 payment certificate is issued and the investigation file may be closed.
How long does a WIBA claim take?
There is no honest one-size-fits-all settlement period.
A straightforward temporary-incapacity claim with complete documents may progress faster than a claim involving:
- Long-term treatment
- Permanent incapacity
- Occupational disease
- Disputed employment
- Conflicting medical reports
- A fatality
- Several dependants
- Missing payroll records
- A workplace investigation
- An objection to the Director’s decision
The employer can reduce avoidable delays by reporting promptly, keeping a complete claim file and responding quickly to document requests.
Never publish a guaranteed settlement timeline unless it appears in the specific insurer’s written service commitment and applies to that particular claim.
Why are WIBA claims delayed?
Common causes include:
Late accident reporting
Delayed notification makes it harder to investigate the scene, interview witnesses and verify the employee’s account.
Incomplete DOSH documentation
Missing signatures, blank sections, incorrect dates or absent employer stamps can cause forms to be returned.
Missing medical reports
A claim cannot be assessed properly without evidence of the diagnosis, treatment, recovery period and final outcome.
Treatment is still continuing
Permanent incapacity cannot always be determined until the employee’s condition stabilises.
Missing earnings evidence
Incomplete payroll or casual-worker records can prevent accurate benefit calculation.
Disputed employment
The employer may dispute whether the injured person was an employee, contractor, visitor or unauthorised worker.
Unclear connection to employment
Questions may arise about whether the injury happened during employment or whether an illness was caused by workplace exposure.
Inconsistent information
Differences between the employee’s statement, employer’s report, medical history and witness evidence may trigger investigation.
Unidentified dependants
Fatal claims may be delayed while lawful dependants are identified and their documents verified.
Undeclared employees or occupations
The insurer may need to investigate employees, occupations or earnings that were not properly declared when the policy was arranged.
For broader guidance, read Why Insurance Claims Are Delayed or Declined in Kenya.
What is the difference between WIBA and GPA?
WIBA and Group Personal Accident insurance are not the same.
WIBA addresses an employer’s statutory responsibility for occupational injuries and diseases arising out of and in the course of employment.
GPA normally provides defined accident benefits under the policy and may operate on a broader basis, such as 24-hour accident protection, where that wording has been purchased.
GPA does not automatically replace WIBA. Many employers arrange both:
- WIBA for statutory workplace exposure
- GPA for wider employee accident protection
The policy schedules, insured persons, occupations, territorial limits and benefit structures should be reviewed carefully.
WIBA claim document checklist for employers
Before submitting the claim, check whether you have:
- Completed DOSH 1
- Insurer’s claim form
- Employee’s identification
- Employment contract or engagement evidence
- Payroll and payslips
- Attendance or shift records
- Accident-register entry
- Internal incident report
- Witness statements
- Photographs or CCTV footage
- Initial and subsequent medical reports
- Sick-off documentation
- Police abstract where relevant
- Final medical assessment
- Death and dependency documents for fatal claims
- Receipts for qualifying expenses
- Correspondence with DOSHS
- Copies of every document submitted
The exact requirements will depend on the circumstances. Ask for a written claim checklist at the beginning of the process.
Can an employee or employer object to a WIBA decision?
Where an affected party disagrees with the Director’s decision, the objection and appeal procedures provided under WIBA should be followed.
The Ministry of Labour publishes an OSH/WIBA objection and appeal form through its forms portal.
Do not ignore a DOSHS assessment or demand. Obtain professional guidance promptly because statutory objection periods may apply.
How Imana Insurance Agency supports employers
Imana Insurance Agency Kenya Ltd can help an employer by:
- Notifying the WIBA insurer
- Providing the insurer’s claim form
- Sharing a document checklist
- Explaining the purpose of DOSH documentation
- Coordinating communication with the insurer
- Following up on outstanding requirements
- Helping the employer organise payroll evidence
- Monitoring the claim’s progress
- Clarifying insurer requests
- Supporting WIBA renewal and workforce declarations
- Comparing WIBA and related employee-benefit quotations
Imana does not replace DOSHS, determine incapacity percentages or issue statutory awards. Those responsibilities remain with the authorised medical practitioners, DOSHS and other relevant authorities.
How can employers reduce WIBA claim delays?
Employers should establish a written internal accident procedure before an incident happens.
The procedure should identify:
- Who arranges emergency treatment
- Who contacts DOSHS
- Who notifies the insurer
- Who completes DOSH 1
- Who collects medical records
- Who preserves CCTV and evidence
- Who provides payroll information
- Who communicates with the employee
- Who tracks outstanding documents
- Who implements corrective safety measures
A claim file should be opened immediately for every reported occupational accident, even where the injury initially appears minor.
Small injuries can develop into serious or permanent conditions. Paperwork should not begin only after the employee’s condition worsens.
Compare WIBA insurance quotations in Kenya
WIBA pricing is influenced by:
- Total annual payroll
- Number of employees
- Employee occupations
- Industry and workplace activities
- Exposure to machinery, vehicles or heights
- Claims history
- Territorial exposure
- Required extensions
- Risk-management controls
An office-based employer will generally present a different risk from a construction company, factory, transport operator, security company or logistics business.
Do not compare WIBA quotations using premium alone. Compare:
- Occupations accepted
- Payroll declared
- Benefit basis
- Territorial scope
- Claims procedure
- Medical-expense provisions
- Exclusions
- Extensions
- Insurer service capacity
- Related GPA or Group Life options
Visit the WIBA Insurance Authority Page or submit the Corporate Insurance Quotation Form.
You can also use:
- ImanaInsurance.com for quotation comparison and customer enquiries
- Imana.co.ke for authoritative Kenyan insurance information
- MyKava.co.ke for digital travel and insurance comparison
Frequently asked questions about WIBA claims in Kenya
Who should report a workplace accident?
The employer should report the accident to DOSHS using the prescribed form and notify the WIBA insurer. The employee should inform the employer as soon as possible.
Is DOSH 1 compulsory?
DOSH 1 is the prescribed accident-notification form at the centre of the current DOSHS work-injury process.
Can an employer report the claim after seven days?
A late report should still be submitted immediately, accompanied by an honest explanation. Late reporting may complicate the investigation and should never be treated casually.
Does an employer need to report a minor accident?
An apparently minor injury can worsen. Employers should record every workplace accident and obtain guidance on statutory reporting instead of making assumptions based only on the initial appearance.
Does WIBA cover an employee travelling to work?
The answer depends on the facts, the statutory connection to employment and the policy terms. Ordinary commuting should not automatically be treated as covered or excluded without examining the circumstances.
Does WIBA cover occupational diseases?
WIBA can respond to qualifying occupational diseases, but medical and workplace evidence must establish the required relationship between the disease and employment.
Who determines permanent incapacity?
A qualified medical practitioner assesses the medical impairment, while the Director of Occupational Safety and Health Services administers the statutory compensation process.
Does GPA replace WIBA?
No. GPA and WIBA serve different purposes. Employers may purchase both as part of a wider employee-protection programme.
Can Imana approve a WIBA claim?
No. The insurer and DOSHS handle the relevant insurance and statutory decisions. Imana assists with documentation, communication and follow-up.
Get WIBA claims and quotation support in Kenya
For WIBA claims guidance, policy review or quotation comparison, contact:
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands, Nairobi
Call/WhatsApp: +254 796 209 402
Websites:
- www.imanainsurance.com — quotation comparison and enquiries
- www.imana.co.ke — insurance authority and product information
- www.mykava.co.ke — digital travel and insurance comparison
Imana Insurance Agency Kenya Ltd is a Westlands-based insurance intermediary helping individuals, families and businesses compare insurance quotations from licensed Kenyan insurers across Motor, Medical, WIBA, PSV, Travel, Motorcycle, Cyber, SME/Corporate and other insurance classes.
Author: Raymond Momanyi
Founder & CEO, Imana Insurance Agency Kenya Ltd
Disclaimer: This article provides general information and does not replace the Work Injury Benefits Act, official DOSHS instructions, legal advice or the terms and conditions of a particular insurance policy. Employers should confirm current forms and procedures with DOSHS and their insurer.