- Author: Raymond
- Category: Golfers Insurance in Kenya
Understanding Golfers Insurance Policy Exclusions in Kenya
Learn the common exclusions in golfers insurance policies in Kenya. Understand what is not covered so you can avoid claim surprises and choose the right protection for your game.
Understanding Golfers Insurance Policy Exclusions in Kenya
By Raymond Momanyi
Founder and CEO, Imana Insurance Agency Kenya Ltd
Golfers insurance provides valuable protection for your equipment, personal accident risks and liability on the course. However, every insurance policy has exclusions — situations or items that are not covered.
Understanding these exclusions before you buy (or before you need to claim) helps you avoid disappointment and ensures you have realistic expectations of your policy.
Why Exclusions Matter
Exclusions exist to keep premiums affordable and to define the exact risks the insurer is willing to accept. When a claim falls under an exclusion, the insurer is entitled to decline it, even if the rest of the policy appears comprehensive.
Reading the exclusions section carefully is just as important as reviewing the benefits.
Common Exclusions in Golfers Insurance Policies
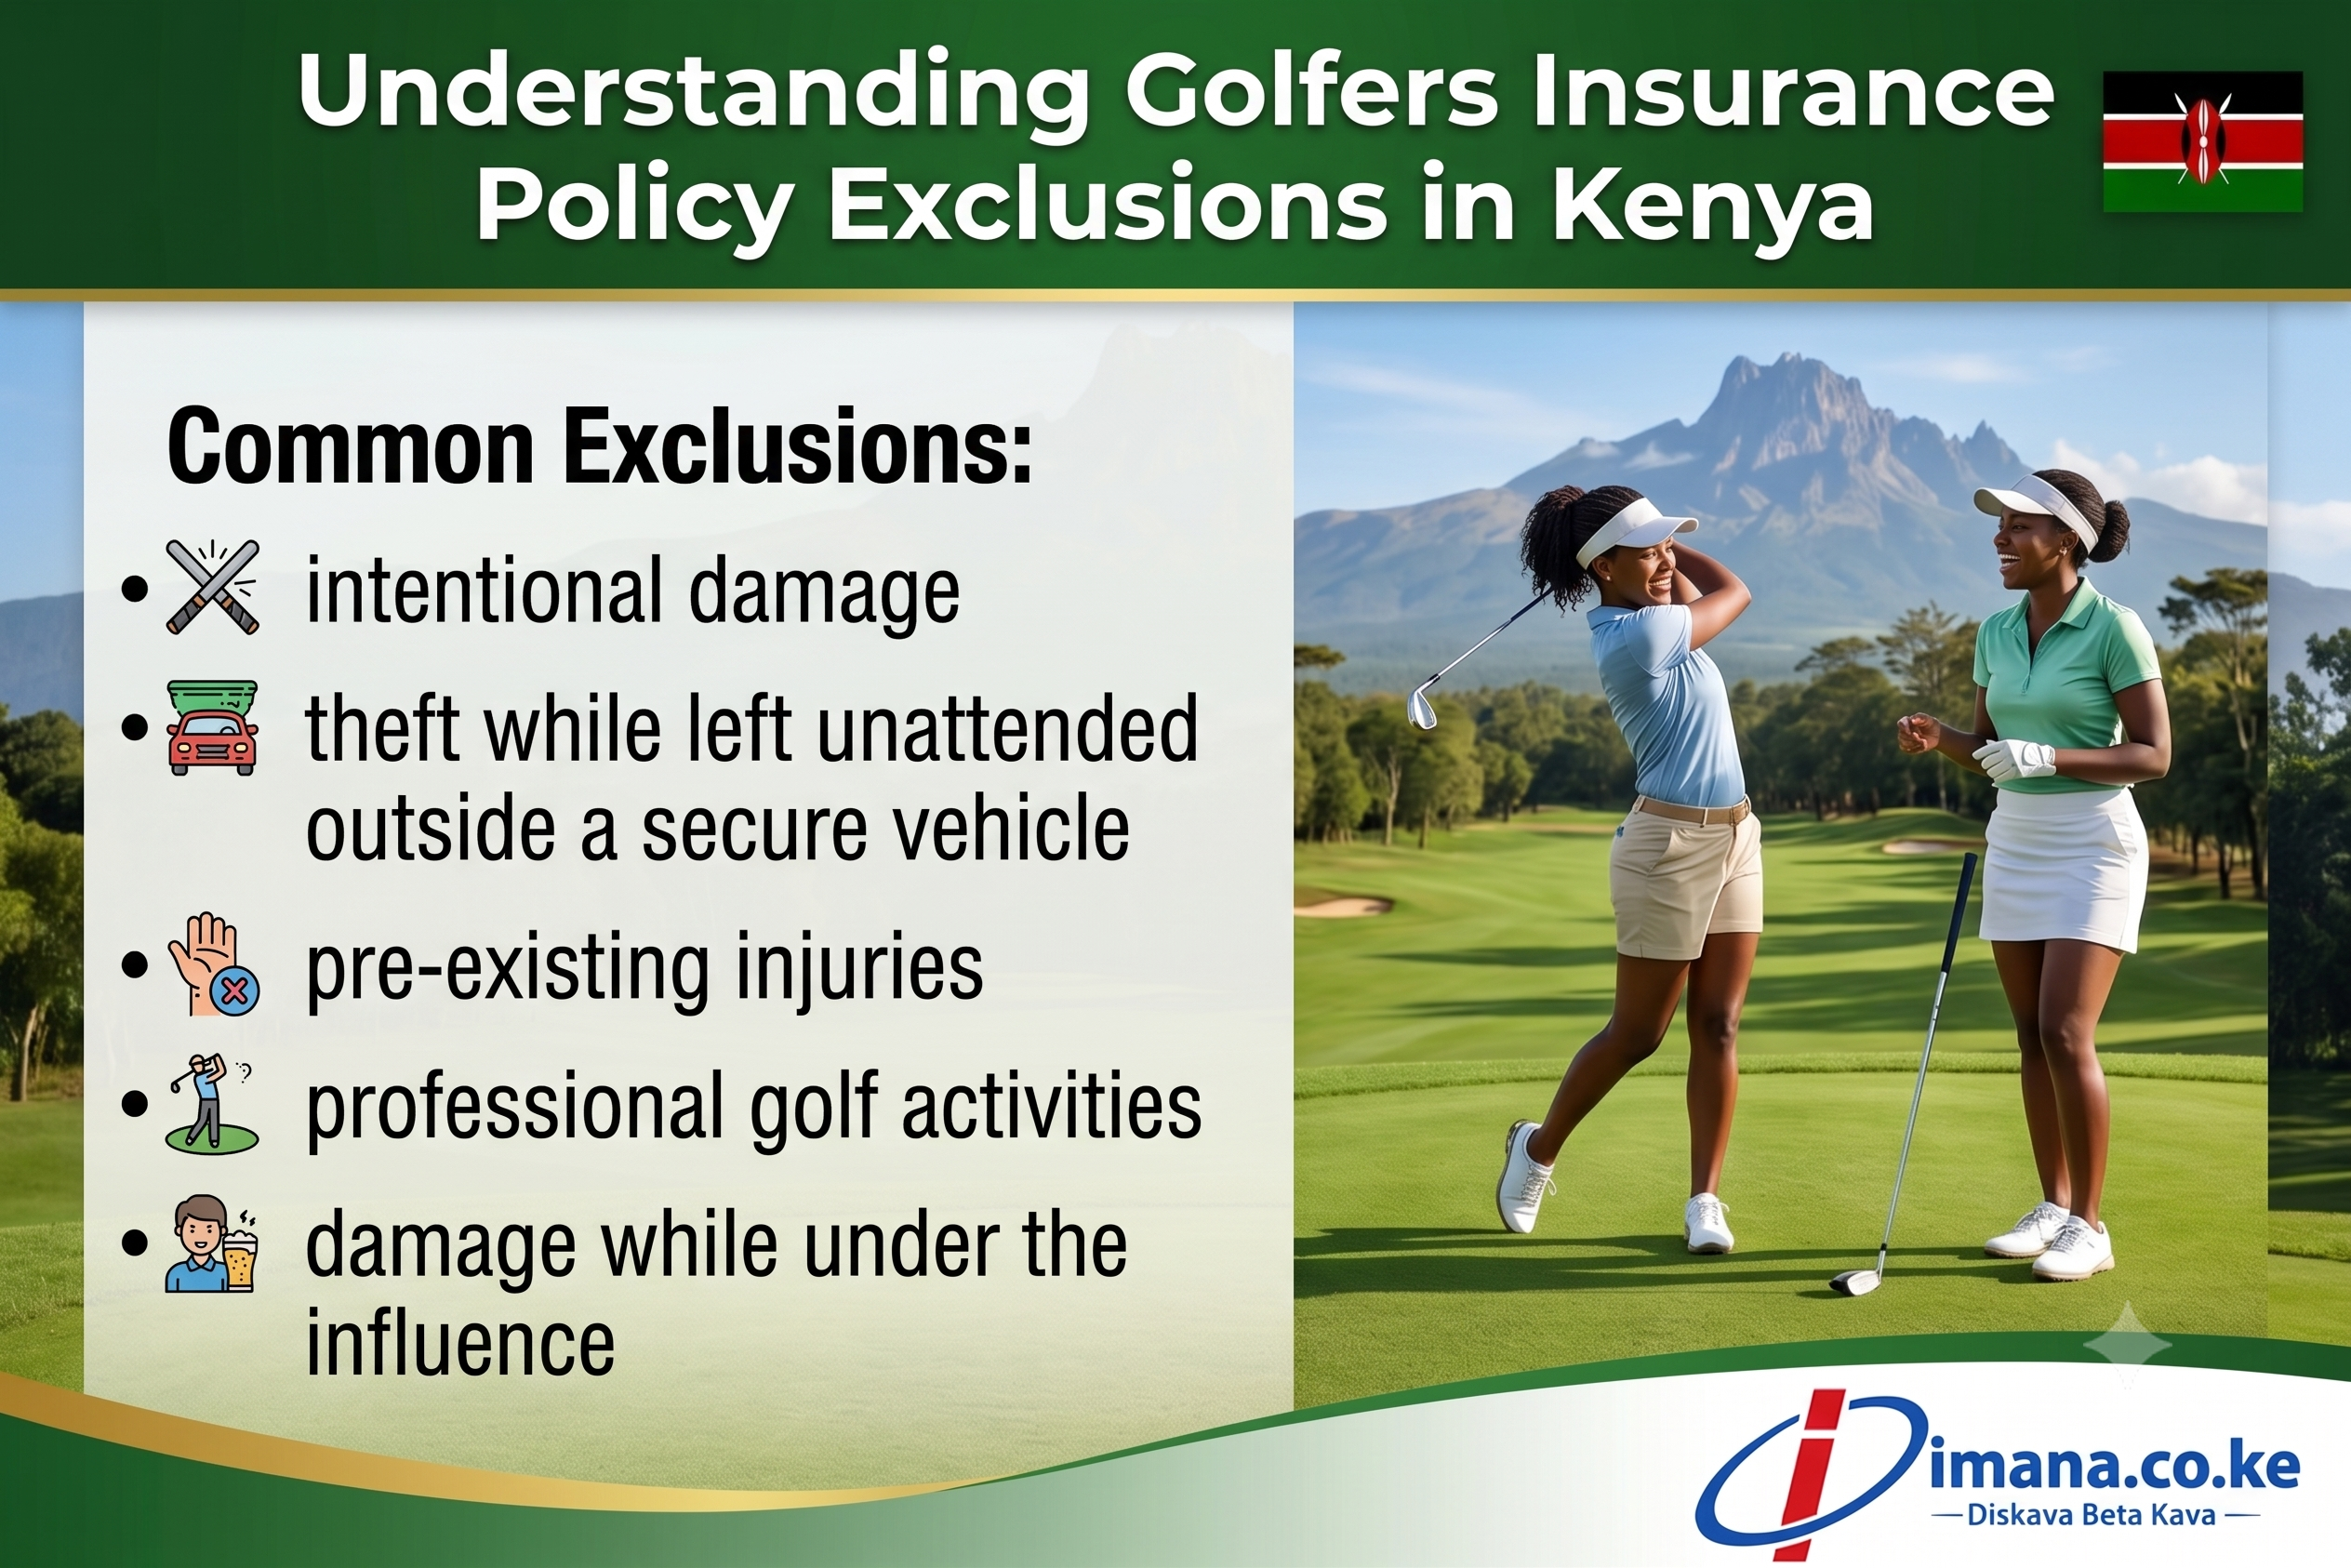
While exact wording differs between insurers, the following exclusions appear frequently in Kenyan golfers policies:
1. Wear and Tear or Gradual Deterioration
Normal aging, gradual damage, rust, corrosion or the natural wearing out of clubs and equipment is not covered. Insurance is designed for sudden and unforeseen events, not maintenance issues.
2. Mechanical or Electrical Breakdown
Failure of equipment due to internal mechanical or electrical faults is usually excluded unless caused by an insured external event such as an accident or fire.
3. Intentional or Deliberate Acts
Any loss or damage caused deliberately by you or with your knowledge is not covered.
4. Pre-Existing Damage
Damage that existed before the policy started, or that you knew about and did not declare, will normally not be covered.
5. Certain High-Value Personal Items
Many policies exclude or heavily restrict items such as jewellery, watches, cash, mobile phones, laptops or other valuables unless they are specifically listed and an additional premium is paid.
6. Loss Outside the Geographical Limit
If your policy is limited to Kenya (or East Africa) and the loss occurs outside that territory, the claim may be declined. Always check whether you need wider territorial cover if you play abroad.
7. Professional or Competitive Play Beyond Policy Scope
Some policies are designed for amateur golfers only. Playing in professional events or for significant prize money may fall outside the cover unless the policy specifically allows it.
8. Failure to Take Reasonable Care
If equipment is left unattended in an insecure place or you fail to take basic precautions, the insurer may reject the claim on the grounds of negligence.
9. War, Terrorism, Nuclear and Related Risks
These standard exclusions appear in almost all general insurance policies unless a specific extension has been purchased.
10. Influence of Alcohol or Drugs
Accidents or losses occurring while the insured is under the influence of alcohol or drugs are commonly excluded.
Other Points to Watch
- Single-item limits: Even when equipment is covered, there is often a maximum amount payable for any one club or item unless it is specially declared.
- Excess: The first portion of every claim (the excess) is payable by you. This is not an exclusion, but it reduces the amount you receive.
- Unreported changes: If your equipment value increases significantly and you do not update the sum insured, under-insurance can reduce your claim settlement.
How to Protect Yourself
- Read the full policy wording, not just the marketing summary.
- Ask your intermediary to explain any exclusion that is unclear.
- Declare high-value or unusual items if you want them covered.
- Keep your sum insured realistic and up to date.
- Take reasonable care of your equipment at all times.
- Confirm territorial limits if you travel for golf.
Final Thoughts
Exclusions are a normal part of insurance. They do not make a policy worthless — they simply define its boundaries. The best approach is to understand those boundaries clearly before you need to rely on the cover.
At Imana Insurance Agency we take time to explain both the benefits and the exclusions of golfers insurance policies. Our goal is that you know exactly what is protected and what is not, so there are no surprises later.
Would you like us to review your current golfers policy or obtain fresh quotations with clear exclusion summaries?
Contact Imana Insurance Agency Kenya Ltd for assistance.
Call or WhatsApp: 0796 209 402 | 0113 619 635 | 0745 218 460
Email: insurance@imana.co.ke
Website: www.imana.co.ke
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Know your cover. Play with confidence.
This article provides general information based on typical market practice in Kenya. Actual exclusions depend on the specific insurer and policy wording. Always refer to your policy schedule and full terms for definitive details.