- Author: Raymond
- Category: Comprehensive Car Insurance in Kenya
Third Party vs Comprehensive Car Insurance in Kenya | Imana Insurance
Understand the difference between third-party and comprehensive car insurance in Kenya. Compare benefits, exclusions and motor insurance quotations with Imana Insurance.
Comprehensive car insurance in Kenya, Third-party motor insurance Kenya, car insurance quotes Kenya, motor insurance renewal, vehicle insurance Kenya, compare motor insurance quotes
Not All Motor Insurance Policies Offer the Same Protection
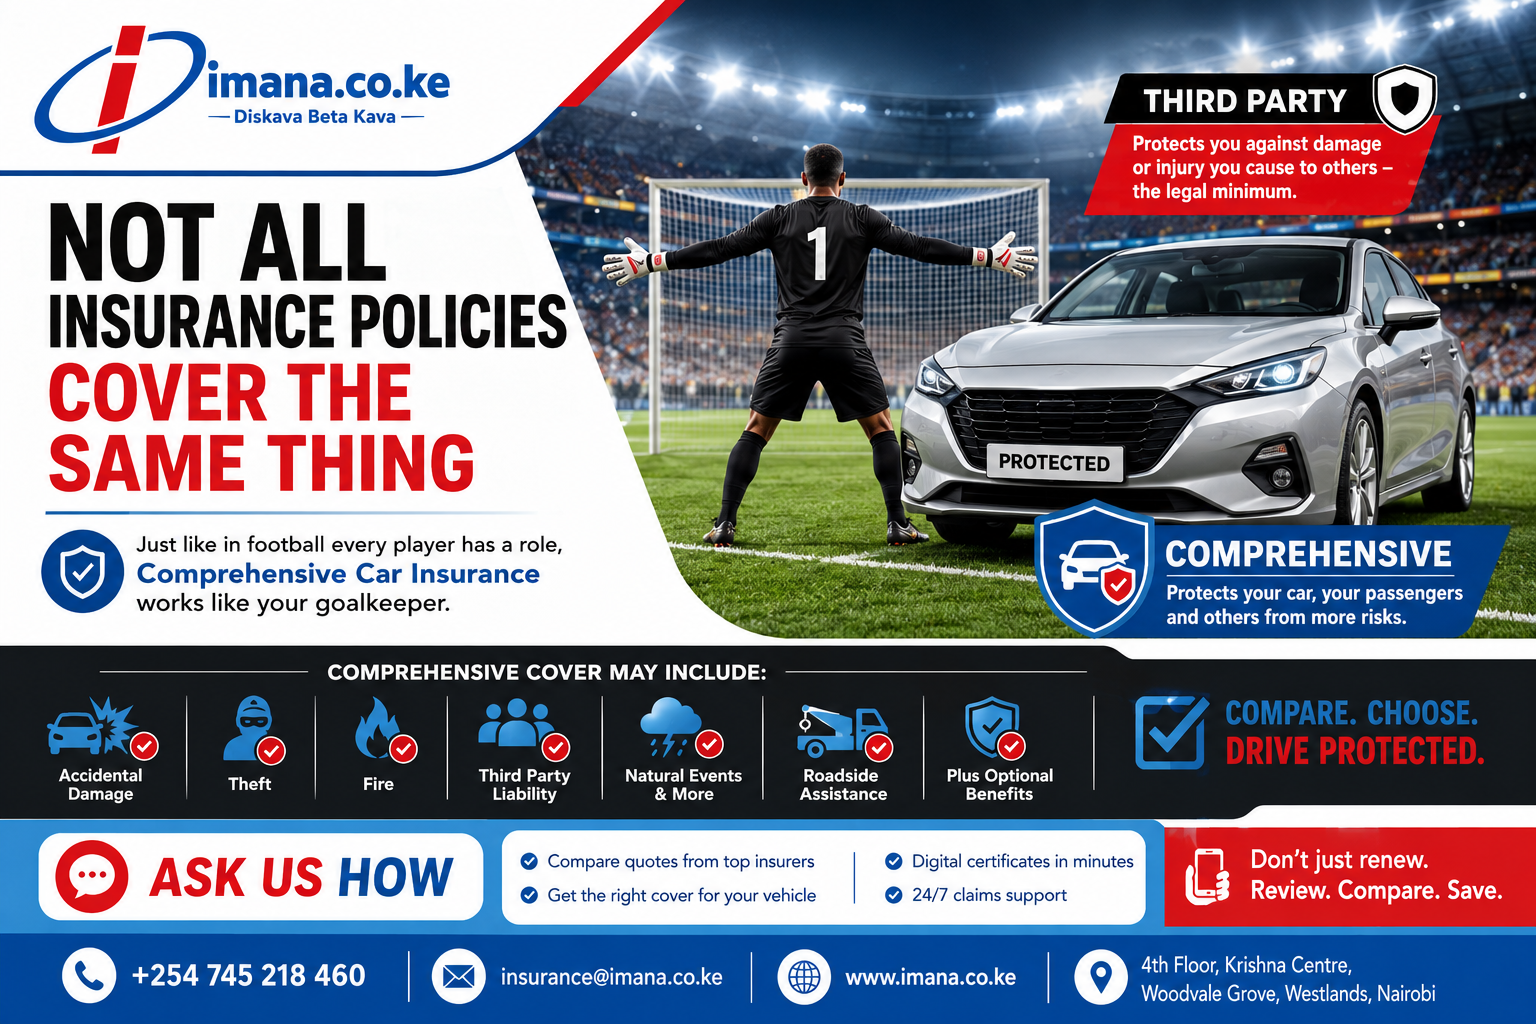
Just like every football player has a specific role, every motor insurance policy is designed to perform a particular function.
A goalkeeper protects the goal. Defenders stop attacks. Midfielders control the game, while strikers are expected to score.
Motor insurance works in a similar way.
A third-party motor insurance policy performs a different role from a comprehensive car insurance policy. Although both are forms of vehicle insurance, they do not provide the same level of protection.
Understanding this difference is important before buying or renewing car insurance in Kenya. Choosing a policy based only on price may leave you financially exposed when an accident, theft or other insured event occurs.
At Imana Insurance Agency Kenya Ltd, we help vehicle owners compare motor insurance quotations from trusted insurance companies and select cover that matches their vehicle, budget and risk exposure.
What Is Third-Party Motor Insurance?
Third-party motor insurance is the most basic form of vehicle insurance.
It is primarily designed to protect you against certain legal liabilities arising when your vehicle causes bodily injury, death or property damage to another person.
For example, when your vehicle is involved in an accident and damages another person’s car, a valid third-party policy may respond to the affected third party’s claim, subject to the terms, limits and conditions of the policy.
However, third-party motor insurance generally does not compensate you for accidental damage to your own vehicle.
This means that when your car is damaged in an accident, you may have to finance the repairs yourself.
What Third-Party Insurance May Cover
Depending on the insurer and policy wording, third-party cover may include:
- Legal liability for injury or death caused to third parties
- Damage caused to another person’s property
- Legal defence costs connected to an insured claim
- Compensation subject to the policy limits and applicable law
Every policy has conditions, exclusions and liability limits. Vehicle owners should therefore read the policy wording instead of assuming that all third-party insurance products are identical.
What Third-Party Insurance Normally Does Not Cover
Third-party insurance generally does not cover:
- Accidental damage to your own vehicle
- Theft of your vehicle
- Fire damage to your car
- Damage caused by floods or other natural events
- Windscreen damage
- Towing and roadside assistance
- Personal belongings left inside the vehicle
- Loss caused by excluded drivers or prohibited vehicle use
Some risks may be available under enhanced products or separate extensions. Always confirm the exact benefits before purchasing the policy.
What Is Comprehensive Car Insurance?
Comprehensive car insurance provides broader protection than third-party insurance.
It usually covers third-party liability while also offering protection for loss of or damage to the insured vehicle, subject to the policy terms, excesses, exclusions and declared vehicle use.
This is why comprehensive car insurance can be compared to a goalkeeper. It provides an additional layer of protection when your own vehicle is threatened by an insured risk.
Comprehensive insurance may be suitable for:
- New vehicles
- Financed or bank-owned vehicles
- High-value cars
- Family vehicles
- Commercial vehicles
- Vehicles that are expensive to repair
- Motorists who cannot easily replace their car after a major loss
What Does Comprehensive Car Insurance Cover in Kenya?
Benefits vary between insurers, but comprehensive motor insurance may include protection against:
1. Accidental Damage
The policy may pay for repairs when your vehicle is damaged in an insured accident.
This is one of the biggest differences between comprehensive and third-party insurance. While third-party cover focuses on damage caused to others, comprehensive cover may also protect your own car.
2. Theft
Comprehensive insurance may compensate you when the insured vehicle is stolen and not recovered, subject to investigation, documentation and policy conditions.
The insurer may also cover damage caused during an attempted theft.
3. Fire Damage
Your vehicle may be covered against loss or damage caused by fire, subject to the exclusions stated in the policy.
4. Third-Party Liability
Comprehensive insurance normally includes third-party protection for injury, death or property damage caused to other road users.
5. Malicious Damage
Some comprehensive policies may cover deliberate damage caused by another person, provided the event falls within the insured risks.
6. Natural Events
Depending on the policy wording, comprehensive insurance may cover certain losses arising from floods, storms and other natural events.
These risks should never be assumed. Vehicle owners must confirm whether they are included, restricted or excluded.
Optional Comprehensive Motor Insurance Benefits
A comprehensive motor insurance policy can often be customised using optional extensions.
These may include:
Excess Protector
An excess is the amount the policyholder may be required to contribute towards a claim.
An excess protector extension may reduce or remove certain excess payments, depending on the policy terms.
Political Violence and Terrorism Cover
Standard comprehensive insurance may exclude losses connected to political violence, riots, strikes, civil commotion or terrorism.
A separate extension may be required for these risks.
Windscreen Cover
This may pay for repair or replacement of the insured vehicle’s windscreen up to the stated limit.
Entertainment System Cover
Factory-fitted or declared vehicle entertainment equipment may be covered up to an agreed limit.
Roadside Assistance
Roadside assistance may include towing, battery support, tyre-change assistance and emergency recovery services.
Courtesy Car
Some insurers may provide or reimburse the cost of temporary transport while the insured vehicle is undergoing repairs following an approved claim.
Personal Accident Benefits
This may provide limited compensation following accidental injury or death involving the insured driver or authorised occupants.
The availability, pricing and limits of these benefits vary between insurance companies.
Third Party vs Comprehensive Car Insurance
FeatureThird-Party InsuranceComprehensive InsuranceThird-party injury liability | Usually included | Usually included
Third-party property damage | Usually included | Usually included
Accidental damage to your car | Generally not covered | May be covered
Theft of your car | Generally not covered | May be covered
Fire damage | Generally not covered | May be covered
Windscreen benefit | Usually not included | May be added
Roadside assistance | Usually not included | May be included or added
Premium cost | Generally lower | Generally higher
Level of protection | Basic | Broader
The exact cover depends on the insurer’s policy wording. The table should therefore be treated as a general comparison rather than a substitute for the insurance contract.
Is Comprehensive Car Insurance Worth It?
Comprehensive insurance may be worth considering when the financial impact of repairing or replacing your vehicle would be difficult to manage.
Imagine that your car is involved in a serious accident.
With third-party insurance, the insurer may deal with covered claims made by the other affected party. However, you may still be responsible for repairing your own vehicle.
With comprehensive insurance, damage to your vehicle may also be covered, subject to the cause of loss, excess, policy conditions and exclusions.
The decision should be based on more than the annual premium.
Consider:
- The current market value of the vehicle
- The cost of spare parts
- The availability of repair specialists
- Whether the car is financed
- Your driving environment
- Your claims history
- How frequently the vehicle is used
- Whether you could replace the car using your own savings
A cheaper policy can become expensive when it leaves a major risk uninsured.
Why You Should Not Renew Car Insurance Automatically
Many motorists renew with the same insurer every year without reviewing the policy.
This may appear convenient, but insurance premiums, benefits, excesses and insurer appetites can change.
Before renewing motor insurance, compare:
- Premium rates
- Minimum premiums
- Excess requirements
- Political violence and terrorism cover
- Windscreen limits
- Towing benefits
- Courtesy-car provisions
- Roadside assistance
- Approved repair arrangements
- Claims-support services
- Policy exclusions
- Payment options
A lower quotation is not automatically a better quotation.
The right comparison should examine both the price and the protection offered.
Common Comprehensive Car Insurance Exclusions
Comprehensive does not mean that every possible loss is covered.
A claim may be rejected when it falls outside the policy terms. Common exclusions or claim complications may involve:
- Driving without a valid licence
- Using the vehicle for an undeclared purpose
- Allowing an unauthorised driver to operate the vehicle
- Driving under the influence of alcohol or prohibited substances
- Mechanical or electrical breakdown
- Wear and tear
- Fraudulent claims
- Undeclared modifications
- Carrying excess passengers or loads
- Using the vehicle outside the permitted geographical area
- Failing to report an accident within the required period
- Political violence where the extension was not purchased
Always disclose the correct vehicle use when requesting a quotation.
A private car used for taxi, delivery, ride-hailing or commercial activity may require a different insurance classification.
Why the Correct Vehicle Value Matters
When purchasing comprehensive motor insurance, the vehicle should be insured at a reasonable market value.
Under-insuring the car to reduce the premium can create problems during a claim. The insurer may apply an average condition or reduce the settlement where the declared value is significantly below the actual market value.
Over-insuring the vehicle may also be unhelpful because insurance is generally intended to restore you to your approximate financial position before the loss—not to create a profit.
A professional motor vehicle valuation may be required, particularly for:
- Older vehicles
- Luxury vehicles
- Imported cars
- Modified vehicles
- Rare models
- Commercial vehicles
- Vehicles whose market value is disputed
Documents Needed for a Motor Insurance Quotation
To obtain an accurate car insurance quotation in Kenya, you may be asked to provide:
- Copy of the logbook
- National ID or passport
- KRA PIN
- Vehicle registration number
- Make and model
- Year of manufacture
- Engine capacity
- Seating capacity
- Estimated market value
- Intended vehicle use
- Previous insurance details
- Claims history
- Preferred extensions and benefits
Additional documents may be required depending on the insurer and class of vehicle.
Why Compare Motor Insurance Quotes Through Imana?
Comparing insurance quotations directly from several insurers can be time-consuming.
Premiums may appear similar while the benefits, excesses and exclusions are completely different.
Imana Insurance Agency Kenya Ltd helps motorists:
- Compare quotations from trusted insurance companies
- Understand third-party and comprehensive cover
- Review benefits, excesses and exclusions
- Identify suitable optional extensions
- Arrange motor vehicle valuations where necessary
- Process policy documentation
- Obtain digital insurance certificates
- Receive guidance during claims
- Review cover before renewal
Our role is not merely to find the cheapest quotation. We help clients identify a policy that provides practical value when a claim occurs.
Frequently Asked Questions
Does third-party insurance repair my car?
Third-party insurance generally does not pay for accidental damage to your own vehicle. It mainly addresses covered liabilities involving other people.
Does comprehensive insurance cover every accident?
Not automatically. The accident must fall within the insured risks, and the policyholder must comply with the policy terms and claims procedures.
Can an old car get comprehensive insurance?
Yes, some insurers offer comprehensive cover for older vehicles. A valuation, inspection, higher excess or special terms may be required.
Is theft covered under third-party insurance?
Theft is generally not covered under basic third-party insurance. Theft protection is commonly associated with comprehensive or third-party fire-and-theft products.
Can I pay comprehensive insurance in instalments?
Some insurers allow comprehensive premiums to be paid in instalments. The available arrangement depends on the insurer, premium amount and agreed payment terms.
How is a comprehensive motor premium calculated?
The premium may be influenced by:
- Vehicle value
- Vehicle class
- Intended use
- Make and model
- Age of the vehicle
- Driver profile
- Claims history
- Chosen extensions
- Insurer’s minimum premium
- Applicable taxes and levies
Which car insurance policy is best?
The best policy is one that matches your vehicle, budget, usage and financial exposure. A quotation should be evaluated using benefits, excesses, exclusions and claims service—not price alone.
Choose the Right Cover Before the Whistle Blows
Insurance matters most when something goes wrong.
Third-party insurance has an important role, but its role is different from that of comprehensive car insurance.
Before renewing your vehicle insurance, ask:
Who protects my own car when an accident happens?
Do not wait until claim time to discover that your policy does not cover the loss you expected it to cover.
Let Imana help you compare, understand and choose the right motor insurance solution.
Get a Free Motor Insurance Quote in Kenya
Imana Insurance Agency Kenya Ltd
📍 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
📞 Call/WhatsApp: +254 745 218 460
📧 Email: insurance@imana.co.ke
🌐 Website: www.imana.co.ke
Request a motor insurance quotation:
- Motor Insurance in Kenya
- Get an Online Insurance Quote
- Request a Corporate Insurance Quote
- Contact Imana Insurance
Ask us HOW.
#ComprehensiveCarInsurance #CarInsuranceKenya #MotorInsuranceKenya #ThirdPartyInsurance #VehicleInsuranceKenya #MotorInsuranceQuote #InsuranceRenewalKenya #ImanaInsurance #MyKava #CompareInsuranceQuotesKenya