- Author: Raymond
- Category: Motor PSV Insurance in Kenya
PSV, Matatu, Taxi & Uber Insurance Prices Kenya
Compare PSV insurance prices in Kenya for matatus, buses, taxis, Uber, Bolt and other ride-hailing vehicles. Understand monthly and annual options.
PSV insurance in Kenya does not have one universal price.
The amount payable depends on whether the vehicle operates as a taxi, Uber, Bolt, matatu, bus, school bus, tour vehicle or another form of public transport.
A saloon car carrying one customer or family at a time does not present the same insurance exposure as a 14-seater matatu operating on a busy urban route. A long-distance bus carrying dozens of passengers presents another level of risk entirely.
This guide answers three important questions:
- How much is PSV insurance in Kenya?
- How much is Taxi, Uber or ride-hailing insurance?
- What is the difference between PSV Matatu or Bus insurance and PSV Taxi or Uber insurance?
What Does PSV Mean in Kenya?
PSV means Public Service Vehicle.
A vehicle is generally treated as a PSV when it carries passengers for hire or reward.
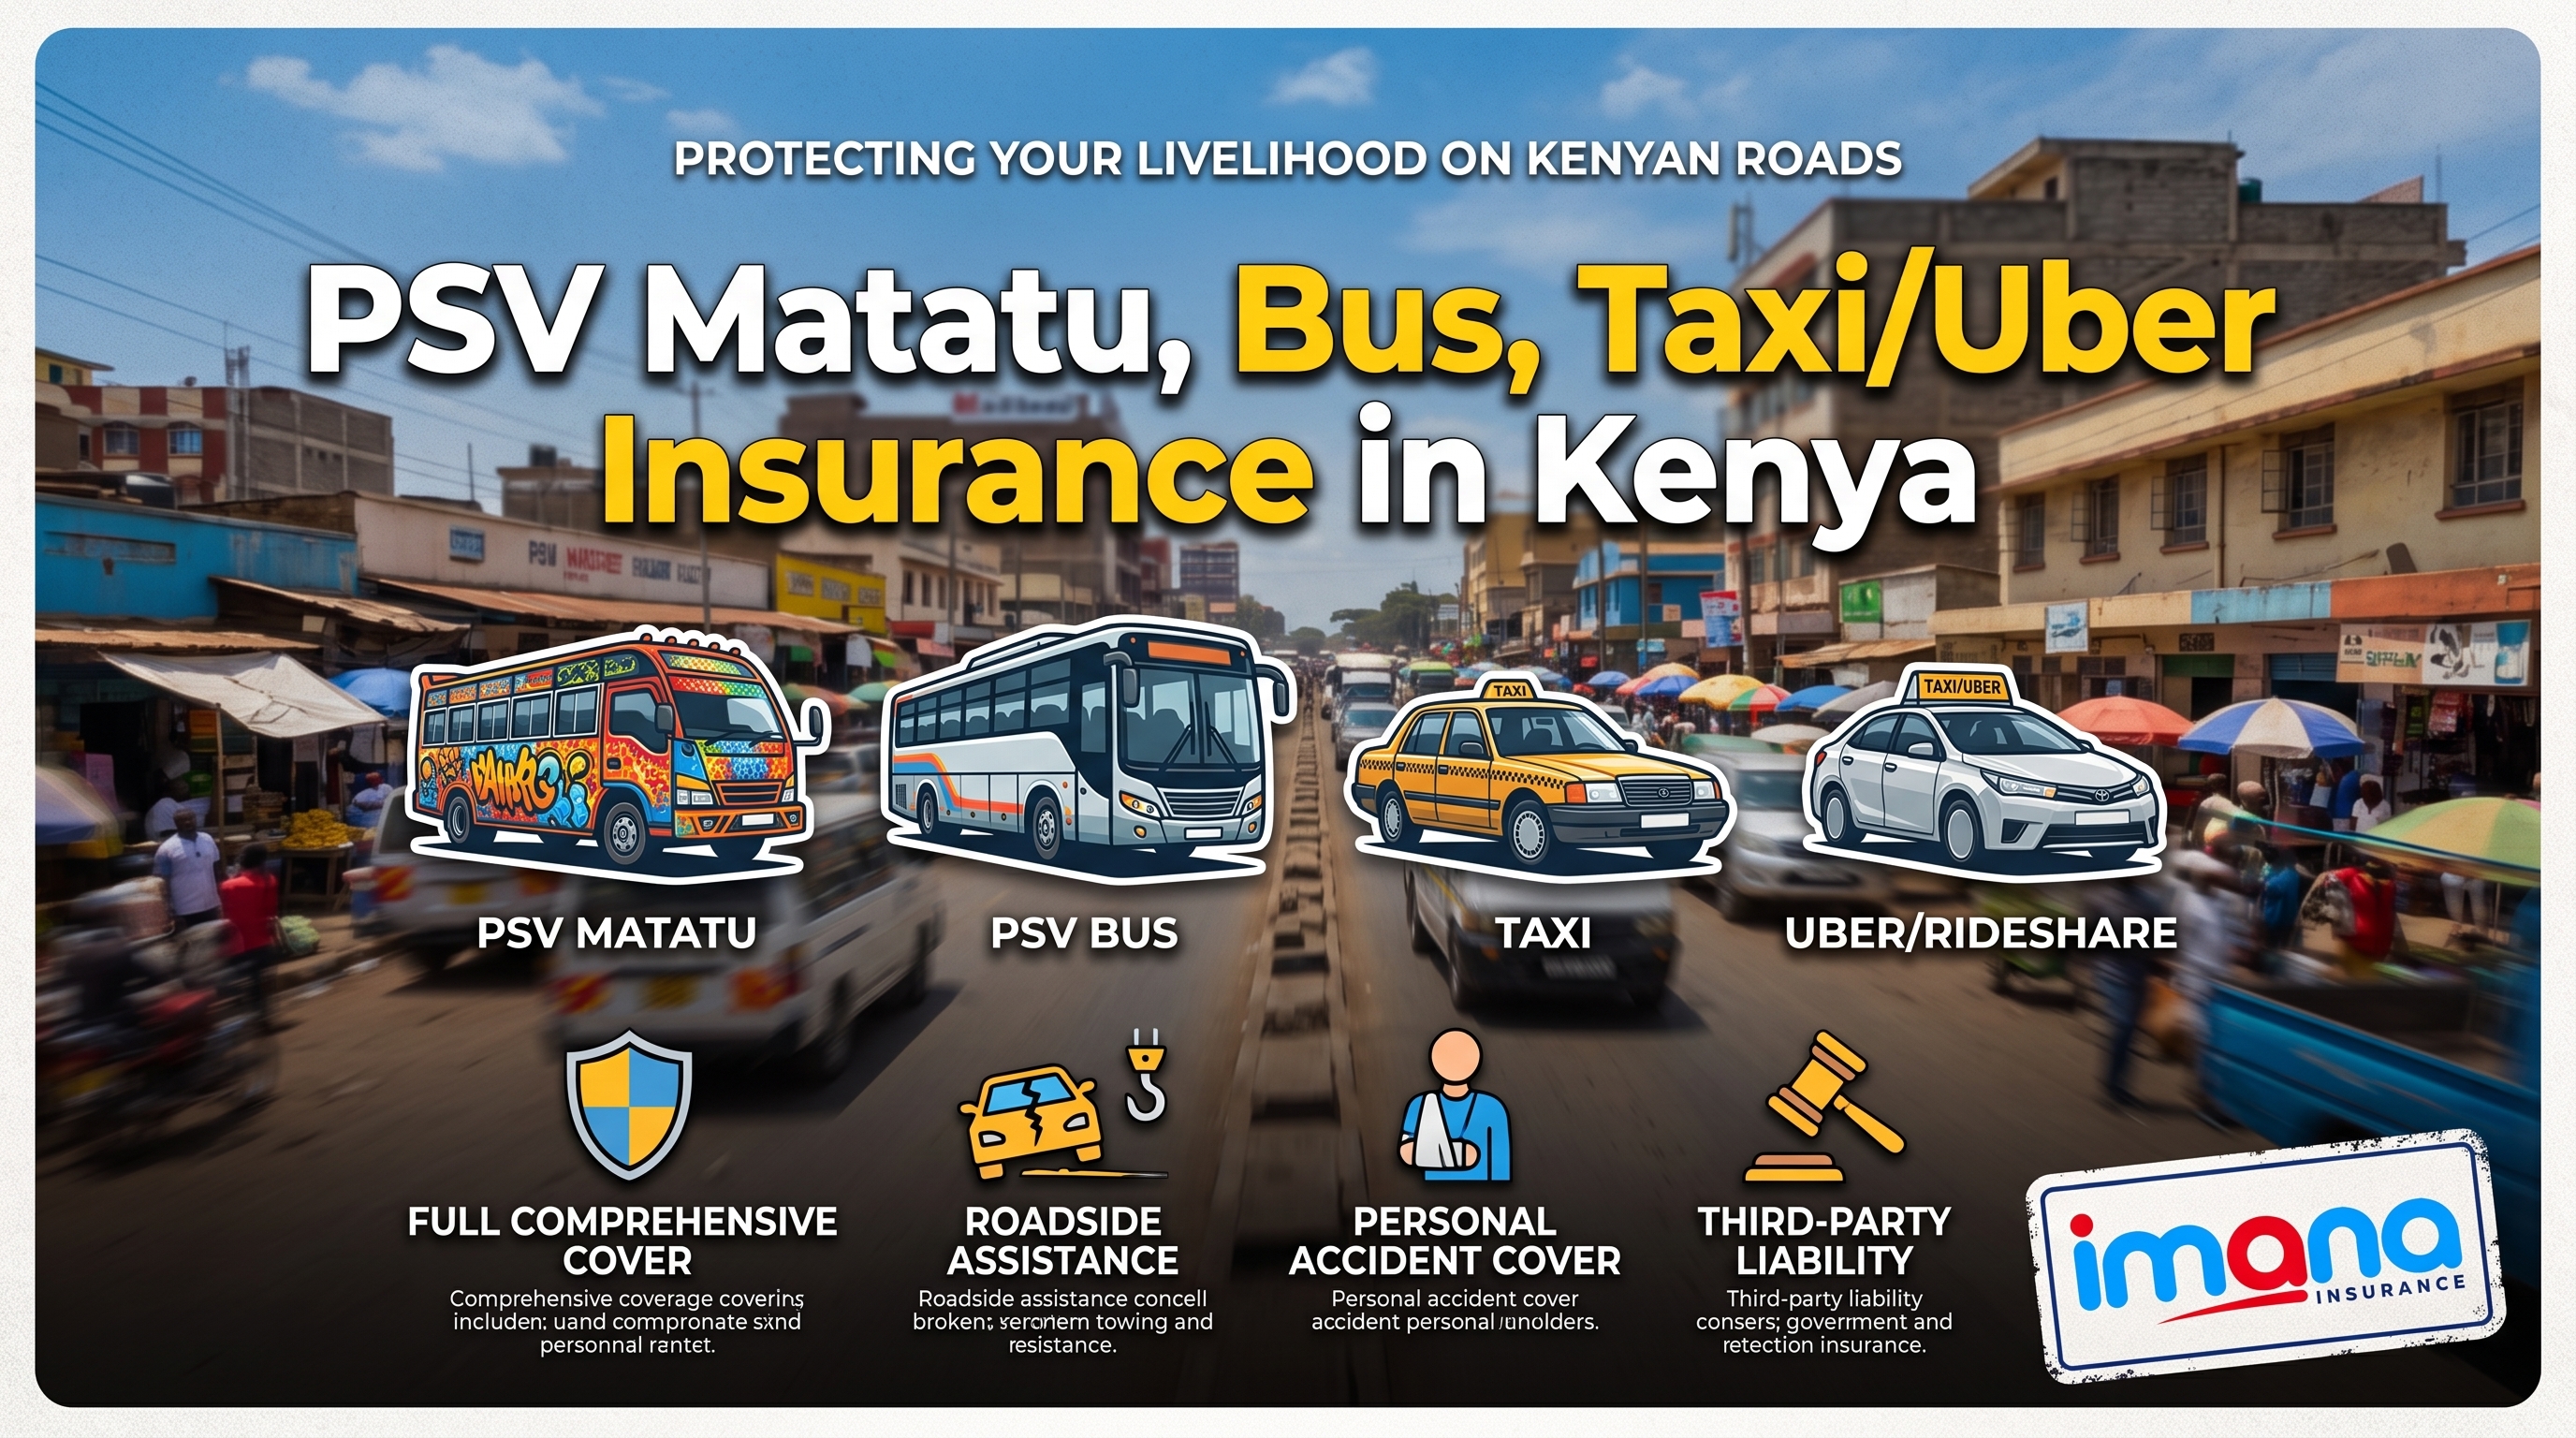
Common PSV categories include:
- Traditional taxis
- Uber vehicles
- Bolt vehicles
- Little Cab vehicles
- Faras and other ride-hailing vehicles
- Chauffeur-driven cars
- Matatus
- Minibuses
- Large passenger buses
- School buses
- Tour vans
- Hotel transfer vehicles
- Staff transport vehicles
- PSV motorcycles and boda bodas
- Passenger-carrying tuk-tuks
Kenyan insurance certificate rules identify matatus, buses, taxis, private and public-hire vehicles, self-drive vehicles and motorcycles carrying fare-paying passengers under the certificate category used for passenger-carrying vehicles.
Why Is the Correct PSV Classification Important?
Insurance follows the vehicle’s declared use.
A vehicle insured for private use should not be used to carry paying passengers. If a private car is placed on Uber, Bolt or another ride-hailing platform, the insurer must be informed and the vehicle placed under the correct PSV category.
Using the wrong motor-insurance class may create serious claim problems because the premium, passenger exposure and policy terms were calculated for a different risk.
Before purchasing cover, explain exactly how the vehicle will be used.
Do not simply say, “It is a Toyota Axio.” The insurer also needs to know whether that Axio is:
- A private family car
- A company vehicle
- A traditional taxi
- An app-based taxi
- A chauffeur-driven vehicle
- A self-drive hire vehicle
The body shape may be identical. The insurance risk is not.
How Much Is PSV Insurance in Kenya?
PSV insurance premiums depend on:
- Type of PSV
- Seating capacity
- Vehicle value
- Year of manufacture
- Area of operation
- Route and distance travelled
- Passenger capacity
- Claims history
- Type of cover
- Period of insurance
- Insurer’s underwriting appetite
- Required add-ons
- Ownership and financing arrangements
Broadly, PSV Taxi and ride-hailing insurance starts lower than matatu and bus insurance because taxis normally carry fewer passengers.
How Much Is Taxi or Uber Insurance in Kenya?
Taxi insurance is commonly classified as PSV Taxi, PSV Chauffeur Driven, Public Hire or another similar category used by the selected insurer.
It can apply to vehicles operating through:
- Uber
- Bolt
- Little Cab
- Faras
- Traditional taxi arrangements
- Hotel transfers
- Corporate chauffeur services
- Airport-transfer businesses
The exact platform name matters less than the commercial use: the vehicle carries passengers for hire or reward.
Third-Party PSV Taxi Insurance Prices
Based on pricing published in existing Imana insurance guides, indicative Third-Party Only premiums may start from approximately:
- KSh 2,000 for one month
- KSh 7,574 for one year
Some current quotations may be presented as approximately KSh 7,500 annually, depending on the insurer and applicable charges.
Imana’s published insurance guides have previously referenced PSV Taxi and ride-hailing cover from about KSh 2,000 for short-term cover and KSh 7,574 annually.
These are starting price indicators—not guaranteed premiums.
The final amount may be higher depending on:
- Vehicle specifications
- Number of passenger seats
- Exact taxi classification
- Short-term or annual cover
- Insurer
- Statutory charges
- Previous claims
- Additional extensions
Comprehensive Taxi and Uber Insurance Prices
Comprehensive PSV Taxi insurance is normally calculated using the vehicle’s market value, insurer’s rate and applicable minimum premium.
Indicative annual premiums may start from approximately KSh 30,000 and rise significantly for high-value vehicles.
A high-value taxi, executive chauffeur vehicle or large ride-hailing vehicle may attract a premium running into hundreds of thousands of shillings, especially where additional benefits are selected.
Imana’s existing comprehensive PSV Taxi guide notes that quotations may range from about KSh 30,000 to KSh 500,000 or more, depending on vehicle value and extensions.
What comprehensive PSV Taxi insurance may cover
Subject to the policy wording, comprehensive cover may include:
- Third-party bodily injury
- Third-party property damage
- Passenger liability
- Accidental damage to the insured vehicle
- Theft
- Fire
- Towing following an insured accident
- Windscreen damage within the policy limit
- Entertainment equipment within the stated limit
Optional extensions may include:
- Excess Protector
- Political Violence and Terrorism
- Courtesy car
- Loss of use
- Road rescue
- Personal Accident
- COMESA Yellow Card
- Increased windscreen limits
- Increased entertainment-system limits
Always check whether an extension is automatically included or charged separately.
How Much Is Matatu Insurance in Kenya?
Matatu insurance is priced differently from taxi insurance because a matatu carries more passengers and may make repeated trips throughout the day.
A 14-seater matatu may attract an indicative Third-Party Only premium of approximately:
- KSh 7,500–KSh 9,000 or more per month
- Approximately KSh 87,000 per year, depending on the insurer and quotation terms
Imana’s existing PSV pricing content places 14-seater matatu Third-Party Only cover at roughly KSh 7,500–KSh 9,000 or more monthly. (imana.co.ke)
The actual price may depend on:
- Licensed seating capacity
- Route
- Urban or long-distance operation
- SACCO or company arrangement
- Vehicle make and model
- Claims history
- Cover period
- Financier requirements
- Insurer acceptance
How Much Is Bus Insurance in Kenya?
Bus insurance depends heavily on seating capacity and use.
A 25-seater minibus, 33-seater bus and 60-seater long-distance coach will not receive the same quotation.
Larger buses generally attract higher premiums because they carry more passengers and may create greater passenger-liability exposure following an accident.
Annual Third-Party Only premiums for larger matatus and buses may exceed KSh 100,000 and can approach or exceed KSh 140,000, depending on capacity, use and insurer terms. Imana’s existing Third-Party price guide notes that larger passenger vehicles may reach this range.
Comprehensive bus insurance is usually calculated using:
- Vehicle value
- Seating capacity
- Type of operation
- Route
- Age of the vehicle
- Claims experience
- Applicable insurer rate
- Minimum premium
- Passenger-liability exposure
- Required extensions
A current quotation is essential because a generic online price cannot account for all these factors.
PSV Taxi/Uber Versus PSV Matatu/Bus
Both categories carry passengers for hire or reward, but they are not the same insurance risk.
PSV Taxi or Uber
PSV Taxi insurance is generally intended for smaller chauffeur-driven vehicles that carry a limited number of passengers per trip.
Examples include:
- Uber
- Bolt
- Little Cab
- Traditional taxis
- Airport taxis
- Chauffeur-driven saloon cars
- Small passenger vans classified as taxis
A taxi typically operates through individual bookings rather than carrying unrelated passengers along a fixed public-transport route.
PSV Matatu or Bus
PSV Matatu and Bus insurance is intended for vehicles transporting multiple fare-paying passengers.
Examples include:
- 14-seater matatus
- 25-seater minibuses
- 33-seater buses
- Large buses and coaches
- Town-service vehicles
- Long-distance passenger vehicles
- SACCO-operated vehicles
Pricing is strongly influenced by seating capacity, passenger exposure, route and type of operation.
The Simple Difference
A PSV Taxi or Uber usually carries fewer passengers through individual bookings.
A PSV Matatu or Bus carries multiple fare-paying passengers, commonly along established routes or scheduled services.
A PSV is not automatically a matatu.
A matatu is one type of PSV, while the wider PSV category also includes taxis, buses, ride-hailing vehicles, passenger motorcycles and other vehicles carrying passengers for hire or reward.
Third-Party Only or Comprehensive PSV Insurance?
PSV operators generally choose between Third-Party Only and Comprehensive cover.
Third-Party Only PSV Insurance
Third-Party Only is the basic form of motor insurance required to address specified third-party liabilities.
For a passenger-carrying vehicle, the policy must reflect the correct PSV use and applicable passenger exposure.
It generally does not pay for accidental damage to the insured vehicle itself.
If the PSV is involved in an accident, Third-Party Only insurance will not ordinarily pay to repair the policyholder’s matatu, bus or taxi.
Kenya’s Motor Vehicle Third Party Risks Act requires a compliant motor policy issued by an authorised insurer and addresses liability arising from death or bodily injury caused through use of a vehicle on a road. Passenger-carrying vehicles used for hire or reward have specific passenger exposure under the law.
Comprehensive PSV Insurance
Comprehensive insurance provides broader protection.
Subject to the wording and exclusions, it may cover:
- Accidental damage to the PSV
- Theft
- Fire
- Third-party liability
- Passenger liability
- Towing and recovery
- Windscreen damage
- Other benefits stated in the policy
A financed taxi, matatu or bus may be required by the lender to maintain comprehensive cover.
Does Third-Party PSV Insurance Cover Passengers?
The policy must be issued under the correct passenger-carrying class.
Passenger liability is a central consideration for vehicles carrying people for hire or reward. However, the applicable legal limits, policy wording and exclusions should be reviewed rather than assumed.
Ask the intermediary to confirm:
- Passenger capacity shown on the policy
- Passenger-liability terms
- Third-party property-damage limit
- Geographical limits
- Permitted vehicle use
- Driver requirements
- Applicable excesses
- Claims-reporting conditions
Can PSV Insurance Be Purchased Monthly?
Some PSV classes can be insured for shorter periods such as one month.
Short-term insurance may help operators manage immediate cash flow, but it should not automatically be assumed to be cheaper over a full year.
Before choosing monthly cover, compare:
- Total cost of repeated monthly renewals
- Cost of annual insurance
- Risk of forgetting the renewal date
- Certificate start and expiry times
- Insurer availability
- Financier requirements
- Continuity of comprehensive cover
- Claims implications
A monthly certificate must be renewed before expiry. Even a short uninsured gap can expose the owner, driver, passengers and business.
Why PSV Insurance Costs More Than Private Car Insurance
A PSV normally has greater road and passenger exposure than a privately used car.
The vehicle may:
- Travel longer distances
- Spend more hours on the road
- Make multiple daily trips
- Carry fare-paying passengers
- Operate in heavy traffic
- Be driven by more than one authorised driver
- Generate income that stops after an accident
- Face greater third-party liability exposure
The insurer prices the actual use, not merely the vehicle model.
What Details Are Needed for a PSV Quotation?
To compare quotations, prepare:
- Vehicle registration number
- Copy of the logbook
- Vehicle make and model
- Year of manufacture
- Seating capacity
- Current market value
- Proposed PSV use
- Operating route or location
- Previous insurance details
- Claims history
- National ID or passport
- KRA PIN
- Company documents where applicable
- Valuation report for comprehensive cover
- Financier’s interest, where applicable
- Preferred commencement date
The insurer may request additional licensing, inspection or operational documents.
Does a Comprehensive PSV Need Valuation?
Generally, yes.
A valuation helps establish the vehicle’s current market value and may identify its condition, accessories and specifications.
The insurer may require valuation:
- Before comprehensive cover begins
- Shortly after policy issuance
- At renewal
- After major modifications
- After a significant claim
- When the insured value changes
Failure to complete a required valuation can affect claim settlement or create underinsurance concerns.
What Is Underinsurance?
Underinsurance occurs when a vehicle is insured below its actual market value.
Some owners reduce the declared value hoping to lower the premium. This can backfire because the insurer may apply the policy’s average condition when settling a partial loss.
The better approach is to use a reasonable current market value supported by a professional valuation.
Important PSV Insurance Add-Ons
Excess Protector
A comprehensive policy may require the insured to pay part of an accidental-damage claim. Excess Protector can cover specified excesses, subject to its terms.
Political Violence and Terrorism
Standard comprehensive insurance may exclude political violence, terrorism, strikes or civil commotion unless the appropriate extension is included.
Loss of Use
A PSV earns income by remaining operational. Loss-of-use cover may provide a stated daily benefit when the vehicle is unavailable following an insured event.
Check the waiting period, maximum number of payable days and daily benefit.
Courtesy Car
A courtesy car may be available for certain PSV Taxi policies, but it should not be assumed to be automatic.
Road Rescue
Roadside assistance may include towing, emergency support or minor roadside services within specified limits.
COMESA Yellow Card
A PSV travelling across participating regional countries may require a COMESA Yellow Card for cross-border third-party liability.
Explore COMESA Yellow Card Insurance.
Common PSV Insurance Mistakes
Avoid:
- Insuring an Uber vehicle as a private car
- Buying taxi cover for a matatu
- Declaring the wrong seating capacity
- Failing to disclose the operating route
- Choosing price without comparing exclusions
- Assuming Third-Party Only covers damage to the PSV
- Forgetting short-term renewal dates
- Ignoring the policy excess
- Omitting Political Violence and Terrorism cover
- Underinsuring the vehicle
- Failing to complete valuation
- Allowing an unauthorised driver to operate the vehicle
- Carrying more passengers than permitted
- Failing to declare vehicle modifications
- Waiting until after an accident to examine the policy
The cheapest certificate can become the most expensive decision when the classification is wrong.
How to Compare PSV Insurance Quotations
Compare more than the premium.
Review:
- Correct PSV category
- Cover period
- Passenger capacity
- Third-party limits
- Comprehensive rate
- Vehicle value
- Basic excess
- Young or inexperienced-driver excess
- Theft conditions
- Political Violence and Terrorism
- Excess Protector
- Loss-of-use benefit
- Courtesy-car benefit
- Road-rescue limits
- Windscreen limit
- Authorised-driver requirements
- Claims process
- Insurer’s PSV underwriting experience
A quotation should clearly show what is included, excluded and optional.
Frequently Asked Questions
How much is PSV insurance in Kenya?
The price depends on the PSV class. PSV Taxi Third-Party Only cover may start from approximately KSh 2,000 monthly or KSh 7,500–KSh 7,574 annually. Matatu and bus premiums are higher and depend heavily on seating capacity.
How much is Uber insurance in Kenya?
Uber and other ride-hailing vehicles may obtain PSV Taxi or Chauffeur Driven insurance. Indicative Third-Party Only prices may start from approximately KSh 2,000 for one month or KSh 7,574 annually.
How much is comprehensive Uber insurance?
Comprehensive PSV Taxi insurance may start from approximately KSh 30,000 annually. The final premium depends on vehicle value, rate, minimum premium, claims history and extensions.
How much is 14-seater matatu insurance?
Indicative Third-Party Only pricing may begin at approximately KSh 7,500–KSh 9,000 or more monthly. An annual quotation may be around KSh 87,000, depending on the insurer and applicable terms.
Is an Uber a PSV?
Yes, where the vehicle carries passengers for hire or reward through the ride-hailing platform. It should be insured under the appropriate PSV Taxi or Chauffeur Driven category.
Is every PSV a matatu?
No. A matatu is a PSV, but the wider PSV category includes taxis, buses, ride-hailing vehicles, passenger motorcycles, tuk-tuks and other vehicles carrying passengers for hire or reward.
Can a private car policy cover Uber use?
A private motor policy is not designed for fare-paying passenger operations. The insurer must be informed and the vehicle placed under the correct PSV classification.
Can matatu insurance be paid monthly?
Short-term options may be available from selected insurers. Availability and price depend on vehicle category, seating capacity and the insurer’s current terms.
Does PSV insurance cover mechanical breakdown?
Ordinary motor insurance generally does not cover routine mechanical or electrical breakdown unless damage arises from an insured event and the policy specifically responds.
What happens if the PSV carries excess passengers?
Overloading may breach traffic requirements and policy conditions. It can also complicate liability and claims investigations.
Request a PSV Insurance Quotation in Kenya
Imana Insurance Agency Kenya Ltd is a Westlands-based insurance intermediary helping individuals, families and businesses compare insurance quotations from licensed Kenyan insurers across Motor, Medical, WIBA, PSV, Travel, Motorcycle, Corporate and other insurance classes.
Imana helps PSV owners compare quotations for:
- Uber and Bolt vehicles
- Traditional taxis
- Chauffeur-driven cars
- 14-seater matatus
- Minibuses
- Large buses
- School buses
- Tour vans
- Staff transport vehicles
- PSV motorcycles
- Passenger tuk-tuks
- PSV fleets
Explore these related Imana resources:
- Motor and PSV Insurance
- Motor Insurance in Kenya
- Request a Motor Insurance Quote
- Comprehensive PSV Taxi Insurance Guide
- Types of Motor PSV Insurance
- Best PSV Matatu, Bus and Taxi Insurance
- Compare Insurance Quotations in Kenya
Contact Imana Insurance Agency Kenya Ltd
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call/WhatsApp: +254 796 209 402
Email: insurance@imana.co.ke
Quotation website: www.imanainsurance.com
Insurance information: www.imana.co.ke
Online comparison platform: www.mykava.co.ke
Compare. Buy. Save.
About the Author
Raymond Momanyi is the Founder and CEO of Imana Insurance Agency Kenya Ltd. His areas of expertise include motor insurance, PSV insurance comparison, medical insurance, WIBA, business risk and insurance claims support.
Disclaimer: The prices in this guide are indicative market-planning figures drawn from existing Imana content. They are not binding quotations or universal tariffs. Premiums, taxes, benefits, limits, exclusions and insurer availability may change according to vehicle use, seating capacity, value, claims history and underwriting requirements.