- Author: Raymond
- Category: Medical Insurance in Kenya
Medical Insurance in Kenya: How to Choose the Right Cover
Healthcare costs in Kenya can rise very fast. One hospital admission, one emergency surgery, one unexpected illness, and savings can disappear like smoke in the wind.
That is why medical insurance is no longer a luxury. It is a practical financial shield for individuals, families, children, employees and retirees.
But choosing medical insurance in Kenya can be confusing. There are inpatient limits, outpatient limits, waiting periods, hospital panels, exclusions, age bands and family structures to think about.
At Imana Insurance Agency Kenya Ltd and MyKava Online Insurance Consultants, we help clients compare and buy medical insurance plans that fit their needs and budget.
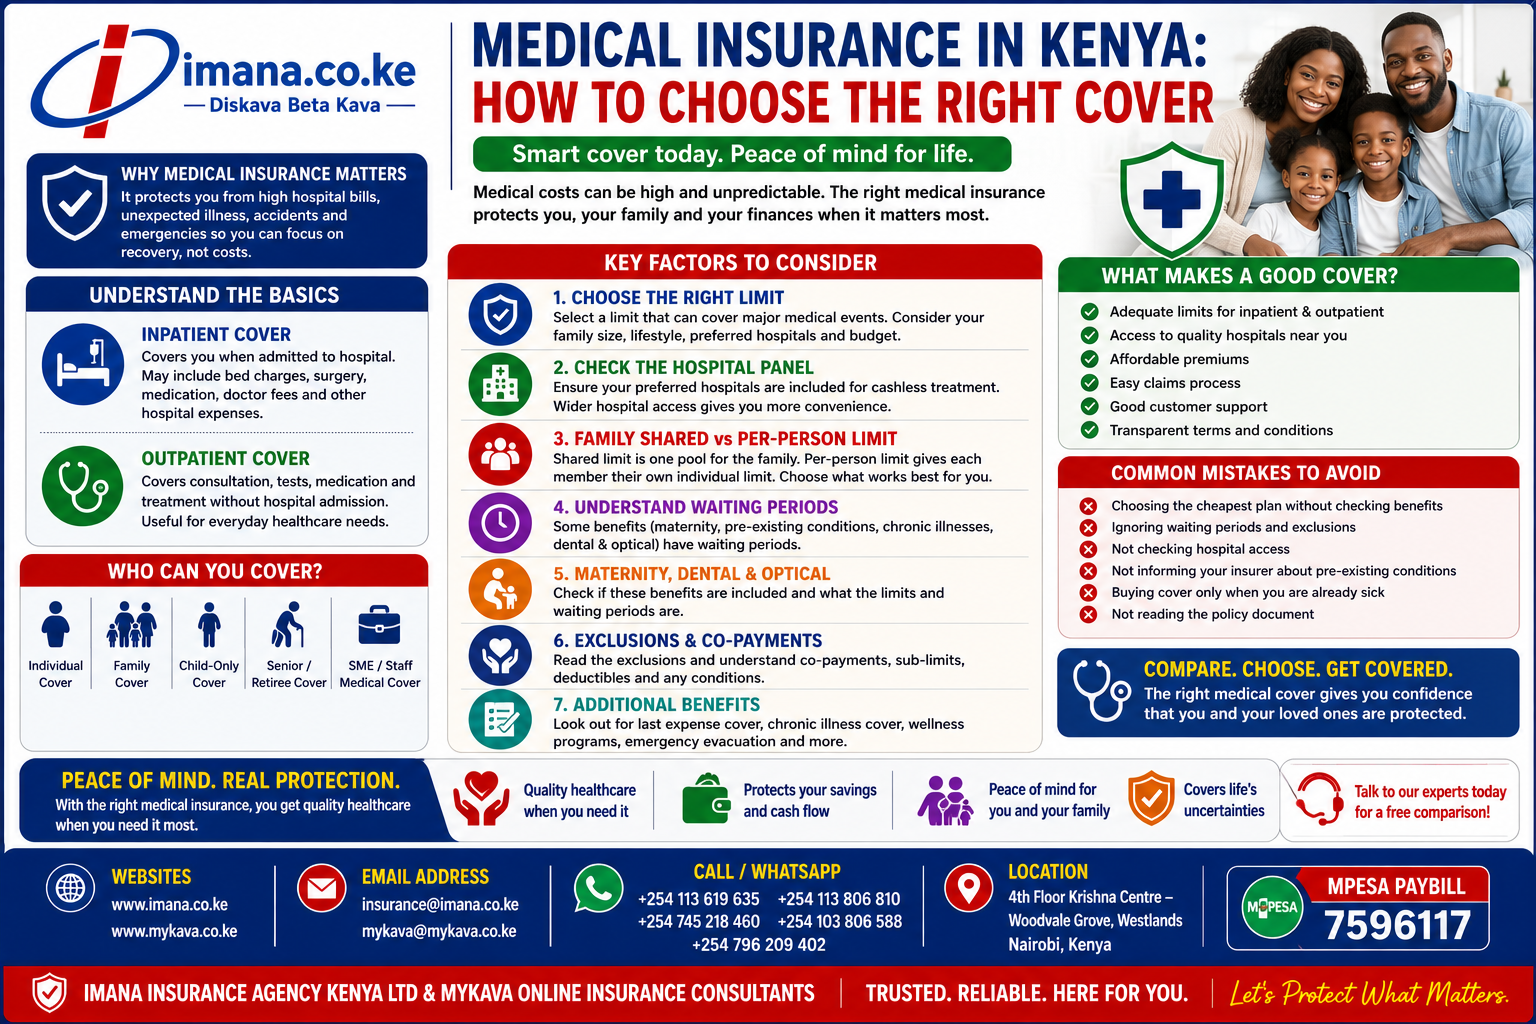
Understand the Difference Between Inpatient and Outpatient Cover
The first thing to understand is the difference between inpatient and outpatient cover.
Inpatient cover applies when you are admitted to hospital. This may include bed charges, surgery, medication, doctor fees and other hospital admission costs, subject to policy limits.
Outpatient cover applies when you visit hospital or clinic but are not admitted. This may include consultation, lab tests, medication and minor procedures, depending on the policy.
If your budget is limited, inpatient cover is usually the first priority because admission bills can be very expensive.
Choose the Right Limit
Medical insurance limits vary. Some plans may offer inpatient cover of KSh 100,000, KSh 300,000, KSh 500,000, KSh 750,000 or more.
Do not choose a limit only because the premium is low. Ask yourself:
- Can this limit handle a serious admission?
- Which hospitals can I access?
- Does the limit apply per person or shared by family?
- Are there sub-limits?
- Does the cover match my family size?
A low limit is better than no cover, but a very low limit may run out quickly during a serious admission.
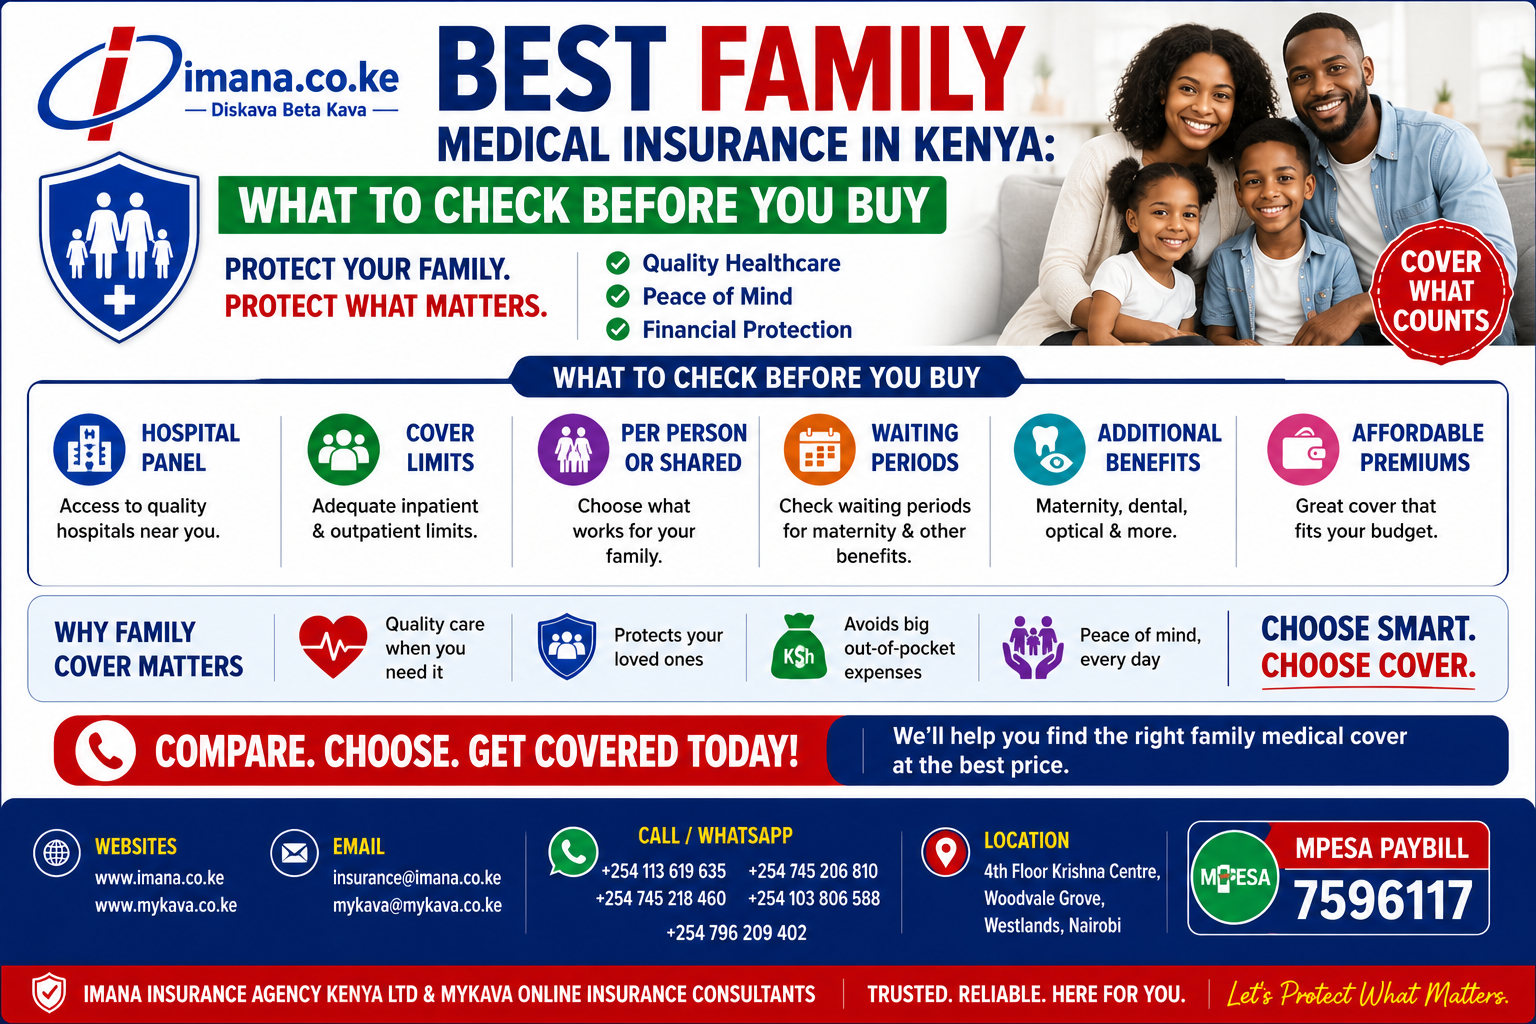
Check the Hospital Panel
A medical cover is only useful if you can access convenient hospitals.
Before buying, check:
- Which hospitals are on the panel?
- Are your preferred hospitals included?
- Are there hospitals near your home or workplace?
- Are there countywide options?
- Does the plan cover mission hospitals, private hospitals or major referral facilities?
For families and SMEs, hospital access is one of the most important decisions.
Consider Age Eligibility
Different medical insurance products have different age limits.
Some covers allow children from birth. Some cover adults up to 65, 70 or 75 years. Senior cover may cost more because the medical risk is higher.
Always confirm the eligible age range before applying.
Understand Waiting Periods
Most medical insurance plans have waiting periods. This means some benefits may not be available immediately after purchase.
Waiting periods may apply to:
- General illnesses
- Chronic conditions
- Maternity
- Pre-existing conditions
- Dental and optical benefits
- Major surgeries
Always ask what is covered immediately and what starts later.
Check Whether the Cover Is Per Person or Shared
This is very important for family medical insurance.
A plan may be structured in two main ways:
Per-person limit:
Each member has their own individual limit.
Family shared limit:
The family shares one pool of benefits.
Both options can work, depending on budget and family needs. Per-person cover gives each member dedicated protection, while shared cover can be more affordable for some families.
Compare Benefits Beyond the Premium
Do not only ask, “How much is the cover?”
Ask:
- What is the inpatient limit?
- What is the outpatient limit?
- Is maternity included?
- Is dental included?
- Is optical included?
- Is last expense included?
- Are chronic conditions covered?
- Which hospitals are available?
- Are there co-payments?
- Are pre-existing conditions covered?
- What exclusions apply?
Cheap cover can become expensive if it does not respond when needed.
Medical Insurance for Children
Parents can consider child-only medical cover where available. This is helpful for parents who want to insure children separately or prioritize the child’s healthcare first.
Children often need outpatient visits, emergency care and admission support, so child medical cover can be a smart move.
Medical Insurance for SMEs and Employers
Employers can use medical insurance to support staff welfare, improve retention and protect employees from unexpected hospital bills.
SME medical cover can be arranged for:
- Employee only
- Employee plus spouse
- Employee plus family
- Custom benefit structures
For businesses, medical cover is both a welfare tool and a serious HR advantage.
Imana Wisdom
The best medical insurance in Kenya is not always the cheapest. It is the one that balances budget, hospital access, benefit limits and real-life medical needs.
Before buying, compare the options properly.
Need help choosing medical insurance in Kenya?
Talk to Imana Insurance Agency Kenya Ltd or MyKava Online Insurance Consultants.
Call/WhatsApp: +254 796 209 402
Websites: www.imana.co.ke | www.mykava.co.ke
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi