- Author: Raymond
- Category: Marine Insurance
How to Get a Digital Marine Cargo Insurance Certificate in Kenya
Learn how to obtain a Digital Marine Cargo Insurance Certificate in Kenya through a licensed insurer. Understand the required documents, payment process, cargo cover, customs verification and claims procedure.
What Is a Digital Marine Cargo Insurance Certificate?
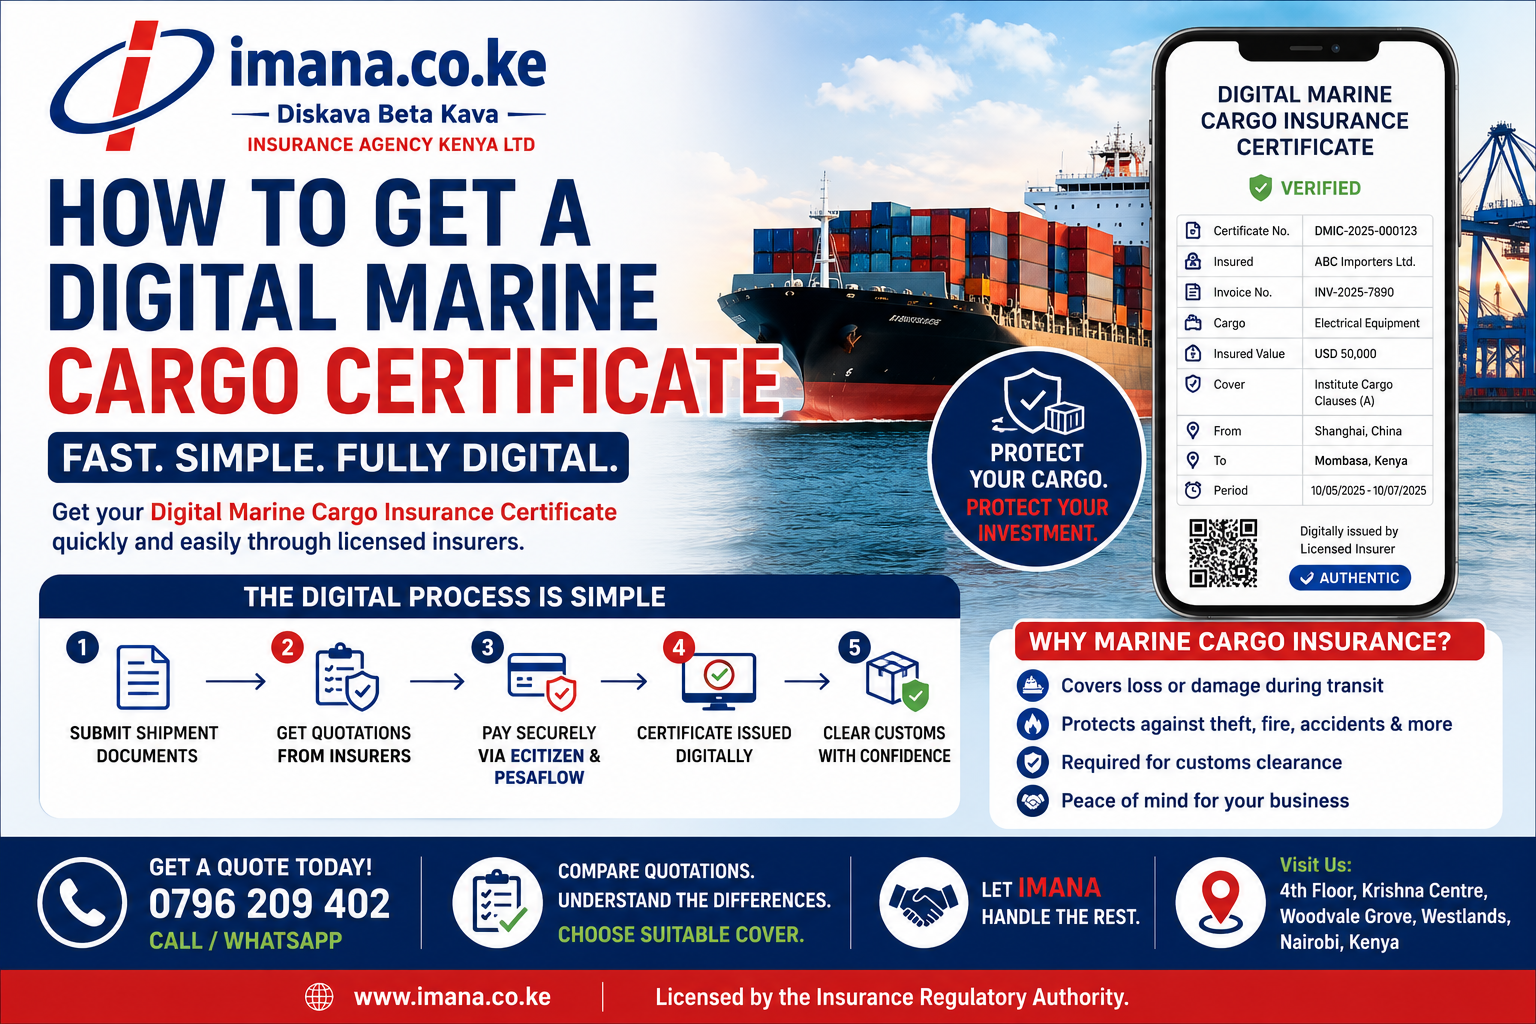
A Digital Marine Cargo Insurance Certificate, commonly abbreviated as DMIC, is electronic evidence that an imported cargo consignment has been insured under an approved marine cargo policy.
The certificate records important information about the shipment, including:
- The importer or insured party
- The insurance company
- Cargo description
- Invoice or declared value
- Mode of transport
- Origin and destination
- Voyage or transit details
- Insurance conditions
- Period of cover
- Certificate number
The Insurance Regulatory Authority published the official Digital Marine Cargo Insurance acquisition procedure on 3 June 2026. The procedure applies to imported cargo consignments and links licensed insurers, the Insurance Regulatory Authority, the Kenya Revenue Authority’s Integrated Customs Management System, eCitizen and the Pesaflow payment gateway. (ira.go.ke)
The digital process is intended to allow the certificate to be issued and verified electronically rather than relying only on manually prepared paper certificates.
A Digital Marine Cargo Insurance Certificate protects the shipment and supports customs compliance—but only when the information matches the actual consignment.
Why Importers Need Marine Cargo Insurance
Imported goods can be damaged or lost at several stages of the journey.
Risks may arise while the cargo is:
- Being loaded at the supplier’s warehouse
- Transported to the export port
- Stored temporarily before shipment
- Loaded onto a vessel or aircraft
- Travelling by sea or air
- Being discharged at the destination
- Stored at a port or bonded facility
- Transported inland to the final destination
- Loaded or unloaded from a truck
Potential causes of loss include:
- Fire
- Collision
- Vessel sinking
- Overturning
- Seawater damage
- Storms
- Theft
- Pilferage
- Rough handling
- Container damage
- Accidental breakage
- Non-delivery
- General average
- Loading or unloading accidents
The seller, shipping line, transporter, freight forwarder and port operator may have limited liability under their contracts. Their financial responsibility may therefore be lower than the actual value of the cargo.
Marine cargo insurance provides direct protection for the importer’s financial interest, subject to the selected cover, exclusions and policy conditions.
Is Marine Cargo Insurance Only for Sea Freight?
No.
The term marine cargo insurance is widely used for goods in international transit, even where part or all of the journey is completed by:
- Air
- Road
- Rail
- Courier
- Sea
- Multimodal transport
The IRA’s digital procedure applies broadly to imported cargo consignments and is integrated into Kenya’s customs-clearance environment. (ira.go.ke)
A shipment arriving through JKIA can therefore require cargo insurance just as goods arriving through Mombasa Port may require it.
The policy must clearly state the mode of transport and the intended transit.
How the Digital Marine Cargo Insurance System Works
The Digital Marine Cargo Insurance process connects several parties.
The importer
The importer provides accurate shipment and identification details and selects suitable insurance.
The clearing agent
KRA advises importers to engage licensed customs clearing agents to process import documentation and declarations through the customs system. (KRA)
The insurance intermediary
A licensed agent or broker can collect the shipment information, obtain quotations, explain the cover and coordinate certificate issuance.
The insurance company
The licensed insurer underwrites the risk, accepts the premium and issues the marine insurance policy and digital certificate.
The Insurance Regulatory Authority
IRA regulates Kenya’s insurance industry and supports the digital marine certificate infrastructure. (ira.go.ke)
Kenya Revenue Authority
KRA processes the import declaration and customs-clearance requirements through its customs systems.
eCitizen and Pesaflow
The official IRA procedure uses the eCitizen payment process and Pesaflow as the designated digital payment infrastructure for the marine insurance workflow. (ira.go.ke)
Step-by-Step: How to Get a Digital Marine Cargo Insurance Certificate
Step 1: Obtain the Shipment Documents
Do not wait until the goods arrive at the port before gathering the documents.
Prepare the basic import records as soon as the supplier confirms the shipment.
KRA lists several documents commonly required to clear imported goods, including:
- Commercial invoice
- Pro forma invoice
- Bill of Lading for sea cargo
- Airway Bill for air cargo
- Certificate of origin
- Freight invoice
- Packing list
- KRA PIN
- Purchase order or contract
- Required permits or licences
- Certificate of Conformity where applicable (KRA)
The exact documents depend on the type of goods and method of transport.
Step 2: Engage a Licensed Clearing Agent
A clearing agent helps the importer process the customs declaration and related import documents.
KRA states that importers need the services of a licensed customs clearing agent to process the import documentation and assist with clearance. (KRA)
The clearing agent can help confirm:
- Correct cargo description
- Customs classification
- Invoice value
- Freight amount
- Import Declaration Form details
- Required permits
- Expected arrival details
- Port or entry point
The insurance information and customs information must agree.
Step 3: Lodge the Import Declaration Information
The clearing agent uses the supplier’s documentation to begin the import declaration process.
KRA explains that the importer ordinarily gives the pro forma invoice to the clearing agent, who lodges the required import declaration information before the later entry, verification and clearance stages. (KRA)
The marine certificate should be connected to the correct consignment.
Check that the following details are accurate:
- Importer’s name
- KRA PIN
- Invoice number
- Cargo description
- Country of origin
- Port of loading
- Destination
- Freight details
- Declared value
- Mode of transport
Step 4: Contact a Licensed Insurer or Insurance Intermediary
Send the shipment documents to a licensed Kenyan insurer, insurance agent or broker.
Do not purchase cover through an unknown person merely because they promise a cheap or immediate certificate.
Confirm:
- Name of the underwriting insurer
- Name and licence status of the intermediary
- Official payment process
- Marine certificate reference
- Policy terms
- Claims contact
IRA maintains registers of licensed insurers and intermediaries and supervises insurance business in Kenya. (ira.go.ke)
Step 5: Provide the Required Cargo Information
The insurer or intermediary may ask for:
- Importer’s full name
- Company registration details
- National ID or passport where applicable
- KRA PIN
- Commercial invoice
- Packing list
- Import declaration details
- Bill of Lading or Airway Bill
- Cargo description
- Number of packages
- Gross weight
- Country of origin
- Port of loading
- Destination port
- Final delivery location
- Vessel or flight information
- Expected departure and arrival dates
- Freight cost
- Insurance value
- Incoterm
- Claims history
- Packaging details
Higher-risk cargo may require additional information.
Step 6: Declare the Goods Accurately
The cargo description should be clear and specific.
Avoid broad descriptions such as:
- General merchandise
- Assorted goods
- Machinery
- Electronics
- Spare parts
A stronger description would identify the actual goods, for example:
- New laptop computers packed in cartons
- Commercial refrigeration equipment
- Motor-vehicle spare parts
- Pharmaceutical products requiring cold storage
- Ceramic floor tiles
- Used passenger motor vehicle
- Industrial printing machine
Accurate descriptions allow the insurer to apply suitable terms and reduce disagreements during a claim.
Step 7: Confirm the Insurance Value
Marine cargo is commonly insured using a value that considers:
- Cost of the goods
- Freight
- Related transit charges
- Insurance
- An agreed uplift for incidental costs or anticipated profit, where provided
The exact valuation formula depends on the insurer and policy.
Do not insure only the supplier’s invoice value where substantial freight, duty-related exposure or other insurable costs should be considered.
Equally, do not inflate the cargo value without justification. Insurance is intended to compensate an actual insured loss, not create profit from a claim.
Step 8: Select the Appropriate Scope of Cover
Marine cargo cover is not identical across all quotations.
A quotation may be offered under different cargo clauses.
Institute Cargo Clauses A
This is generally the broadest of the standard cargo options. It covers accidental physical loss or damage unless the cause is excluded.
It is often described as “all risks,” but exclusions still apply.
Institute Cargo Clauses B
This provides named-peril protection that is broader than Clause C but narrower than Clause A.
Institute Cargo Clauses C
This is a more restricted named-peril option covering major specified events.
The most suitable option depends on:
- Nature of goods
- Packaging
- Value
- Journey
- Mode of transport
- Fragility
- Theft exposure
- Storage
- Budget
High-value electronics, fragile goods, machinery or theft-attractive cargo may require broader protection and specific extensions.
Step 9: Review Important Extensions
Depending on the shipment, consider whether the quotation includes:
- Theft and pilferage
- Non-delivery
- Breakage
- Leakage
- Loading and unloading
- Temporary storage
- War risks
- Strikes, riots and civil commotion
- Inland transit
- Warehouse-to-warehouse protection
- Refrigeration breakdown
- Temperature variation
- Used machinery conditions
- Duty insurance
- Debris removal
- Survey fees
Do not assume every extension is included in the base quotation.
Step 10: Review the Quotation
Before paying, check:
- Cargo description
- Insured value
- Origin
- Final destination
- Mode of transport
- Policy clauses
- Extensions
- Premium
- Taxes and levies
- Excess
- Exclusions
- Transit period
- Storage conditions
- Claims-notification procedure
Compare quotations on the same basis.
A cheaper quotation may have:
- Narrower cargo clauses
- Higher excess
- No theft cover
- No breakage cover
- Shorter storage allowance
- Restricted inland transit
- More warranties
Step 11: Pay Through the Approved Digital Process
Once the quotation is accepted, payment is processed through the approved system.
The official IRA procedure states that payment is initiated through the eCitizen payment API using the Pesaflow gateway. (ira.go.ke)
Use the correct payment reference.
Keep:
- Payment confirmation
- Official receipt
- eCitizen transaction reference
- Insurer’s confirmation
- Communication with the intermediary
Avoid sending the premium to an individual’s personal account unless the insurer has officially confirmed that payment channel.
Step 12: Certificate Generation and Electronic Verification
After payment and underwriting approval, the insurer generates the Digital Marine Cargo Insurance Certificate.
The official process links the insurer, IRA, eCitizen payment infrastructure and KRA’s ICMS environment. (ira.go.ke)
The certificate details can therefore be verified electronically during customs processing.
The importer should still obtain a copy for their records.
Step 13: Check the Certificate Carefully
Confirm:
- Insured name
- Importer’s KRA PIN
- Insurer
- Certificate number
- Invoice number
- Cargo description
- Insured value
- Bill of Lading or Airway Bill
- Origin
- Destination
- Vessel or flight
- Period of cover
- Cargo clauses
- Extensions
Request correction immediately where any detail is wrong.
Do not wait until the customs declaration is being processed.
Step 14: Share the Certificate With the Clearing Agent
Give the clearing agent:
- Certificate copy
- Certificate number
- Payment confirmation
- Policy details
- Any relevant endorsement
The agent should confirm that the digital certificate matches the customs declaration and appears correctly within the applicable workflow.
Step 15: Keep the Full Policy Documentation
The digital certificate is evidence of insurance, but it may not contain every policy condition.
Keep:
- Quotation
- Policy schedule
- Digital certificate
- Full policy wording
- Cargo clauses
- Extensions
- Payment receipt
- Invoice
- Bill of Lading or Airway Bill
- Packing list
- Correspondence
These documents become important if the cargo is damaged or lost.
How Long Does It Take to Obtain the Certificate?
Where the importer provides complete and consistent information, the digital process can be completed quickly.
Delays may arise from:
- Missing import declaration information
- Incorrect KRA PIN
- Invoice mismatch
- Wrong cargo description
- Unclear Incoterms
- Incorrect insured value
- High-risk goods
- Missing permits
- Payment-reference errors
- Portal interruptions
- Insurer underwriting questions
The best approach is to arrange cover before the cargo arrives.
Last-minute applications can create pressure and increase the risk of errors.
Which Goods Can Be Covered?
Marine cargo insurance may be arranged for goods such as:
- Motor vehicles
- Spare parts
- Machinery
- Electronics
- Building materials
- Furniture
- Clothing
- Food products
- Agricultural inputs
- Medical equipment
- Pharmaceuticals
- Raw materials
- Industrial chemicals
- Household goods
- Solar equipment
- Telecommunications equipment
Some cargo requires specialised underwriting.
Examples include:
- Perishable goods
- Frozen products
- Pharmaceuticals
- Hazardous materials
- Used machinery
- Livestock
- Fragile glass
- High-value jewellery
- Bulk commodities
- Project cargo
- Oversized equipment
Never conceal the nature of the goods to obtain a lower premium.
What Are Incoterms, and Why Do They Matter?
Incoterms help define responsibilities between the buyer and seller, including transport costs, delivery points and risk transfer.
Common arrangements include:
- EXW
- FCA
- FOB
- CFR
- CIF
- CPT
- CIP
- DAP
- DDP
Insurance responsibility can differ according to the selected term.
CIF and CIP shipments
Under CIF or CIP arrangements, the overseas seller ordinarily arranges a level of cargo insurance.
However, Kenyan importers should confirm whether the insurance arrangement satisfies the applicable local digital-certificate requirements and whether additional local placement is necessary.
The official Kenyan digital process is implemented through licensed insurers, IRA, KRA ICMS, eCitizen and Pesaflow. (ira.go.ke)
Before signing a supply contract, ask:
- Who arranges insurance?
- Which insurer issues the policy?
- What cargo clauses apply?
- What is the final insured destination?
- Does the policy integrate with Kenya’s digital process?
- Will local insurance create duplicate cost?
- Should the procurement term be reviewed?
Do not change international purchasing terms without considering the full commercial, tax, logistics and legal consequences.
Does “Warehouse to Warehouse” Mean Unlimited Cover?
No.
Warehouse-to-warehouse cover generally follows the ordinary course of transit from the agreed starting point to the stated destination, subject to the policy wording.
Cover may end when:
- Goods reach the named destination
- Goods are placed into storage outside the ordinary course of transit
- The insured uses the location for distribution
- A specified number of days expires after discharge
- The journey is intentionally interrupted
- The cargo is redirected without insurer approval
The certificate should therefore state the true final destination.
Do not write “Mombasa Port” where the goods are intended to continue to a warehouse in Nairobi unless the cover and certificate are structured accordingly.
Single-Shipment Certificate vs Marine Open Cover
Single-shipment insurance
This covers one specified consignment.
It may suit:
- Occasional importers
- One-off machinery purchases
- Personal effects
- A single vehicle
- Special project cargo
A separate certificate is issued for each shipment.
Marine open cover
Marine open cover is designed for businesses making frequent shipments.
The business agrees an annual arrangement, then declares each consignment as it occurs.
It may provide:
- Pre-agreed cargo terms
- Faster certificate issuance
- Consistent rates
- Automatic protection within declared limits
- Easier administration
The importer must still declare every shipment accurately and within the agreed timeframe.
An undeclared consignment may create difficulties during a claim.
What Is Normally Excluded?
Common exclusions may include:
- Wilful misconduct
- Ordinary leakage
- Ordinary loss in weight
- Wear and tear
- Inherent vice
- Poor or insufficient packaging
- Delay
- Insolvency of specified transport parties
- Unseaworthiness known to the insured
- War unless extended
- Strikes and civil disturbance unless extended
- Nuclear risks
- Temperature change without specialised cover
- Mechanical or electrical derangement without external damage
- Fraud
- Illegal trade
- Sanctions-related risks
The actual exclusions depend on the cargo clauses and insurer.
Packaging Matters
Cargo insurance does not excuse poor packaging.
The insurer may examine whether the goods were packed appropriately for:
- Sea movement
- Road vibration
- Air transport
- Multiple handling
- Stacking
- Moisture
- Temperature
- Weight
- Fragility
Packaging records may include:
- Photographs
- Supplier specifications
- Container-loading reports
- Seals
- Pallet information
- Crate details
- Temperature records
Weak packaging can contribute to a claim rejection where the loss arises from insufficient or unsuitable preparation.
What to Do When Cargo Arrives Damaged
Do not sign a clean delivery receipt
Record visible loss or damage before accepting delivery.
Take photographs and videos
Capture:
- Container
- Seal
- Packaging
- Damaged goods
- Water marks
- Impact points
- Vehicle or vessel details
- Delivery environment
Notify the insurer immediately
Do not wait until the cargo has been unpacked, repaired, sold or destroyed.
Request a survey
The insurer may appoint a marine surveyor to inspect the goods.
Notify the carrier
Send a written notice of loss to the:
- Shipping line
- Airline
- Transporter
- Freight forwarder
- Port operator
- Warehouse operator
This helps preserve recovery rights.
Prevent further damage
Separate wet goods, arrange safe storage or take other reasonable steps with insurer guidance.
Preserve damaged goods and packaging
Do not discard evidence before the insurer or surveyor approves disposal.
Documents Required for a Marine Cargo Claim
The insurer may request:
- Claim form
- Digital Marine Cargo Insurance Certificate
- Policy schedule
- Commercial invoice
- Packing list
- Bill of Lading or Airway Bill
- Import declaration documents
- Delivery note
- Port records
- Survey report
- Photographs
- Correspondence with the carrier
- Notice of loss
- Repair quotation
- Replacement quotation
- Proof of payment
- Customs entry
- Police report for theft
- Container seal records
- Temperature records where applicable
A claim may be delayed where these records are missing.
Common Mistakes Importers Should Avoid
Arranging insurance after the loss
Insurance must be arranged before the risk occurs.
Waiting until the cargo arrives
Last-minute applications can delay documentation and customs processing.
Using an incorrect cargo value
Underinsurance can reduce claim settlement.
Giving a vague cargo description
The policy should identify the actual goods being transported.
Ignoring the final destination
Cover may end before the cargo reaches the importer’s warehouse.
Choosing the cheapest cargo clause
Restricted cover may not protect theft, breakage or handling damage.
Failing to declare used machinery
Used equipment may require special conditions or inspection.
Ignoring packaging requirements
Poor packaging can affect a claim.
Failing to check the digital certificate
Small errors can create customs or claims complications.
Assuming the carrier will pay everything
Carrier liability may be limited.
Discarding damaged goods
The insurer must be allowed to inspect and assess the loss.
Failing to notify the carrier
This can weaken recovery rights.
How to Compare Marine Cargo Insurance Quotations
Give every insurer the same:
- Cargo description
- Invoice value
- Freight amount
- Origin
- Destination
- Mode of transport
- Packaging
- Incoterm
- Required cargo clauses
- Claims history
Then compare:
- Total premium
- Insured value
- Cargo clauses
- Excess
- Theft protection
- Breakage
- Non-delivery
- War and strikes
- Storage period
- Inland transit
- Loading and unloading
- Temperature risks
- Claims procedure
- Survey requirements
- Exclusions
The lowest premium does not automatically provide the most appropriate protection.
How Imana Helps Importers Obtain Digital Marine Certificates
Imana Insurance Agency Kenya Ltd helps importers, manufacturers, traders, logistics businesses and individuals obtain marine cargo quotations and coordinate Digital Marine Cargo Insurance Certificate issuance.
The process may include:
- Reviewing the shipment documents.
- Confirming the cargo description.
- Establishing the insurable value.
- Reviewing the Incoterm.
- Comparing quotations from suitable insurers.
- Explaining cargo clauses and exclusions.
- Coordinating digital payment.
- Confirming certificate issuance.
- Checking the certificate details.
- Supporting claim notification where cargo is damaged.
Imana can assist with:
- Sea cargo
- Airfreight
- Imported motor vehicles
- Industrial machinery
- Electronics
- Project cargo
- Commercial goods
- Containerised cargo
- Inland transit
- Marine open cover
- Single-shipment certificates
Marine Cargo Insurance in Westlands, Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Imana serves importers in Nairobi, Mombasa and other parts of Kenya through digital documentation channels.
Website: Imana.co.ke
Call or WhatsApp: +254 796 209 402
Compare quotations. Understand the cargo clauses. Choose suitable protection. Let Imana handle the rest.
Frequently Asked Questions
What is a Digital Marine Cargo Insurance Certificate?
It is electronic evidence that a specified imported cargo consignment has been insured under a marine cargo policy.
Who issues the digital certificate?
It is issued by a participating licensed insurance company after underwriting approval and payment.
Is the process connected to KRA?
Yes. IRA’s official procedure links licensed insurers, KRA’s Integrated Customs Management System, eCitizen, Pesaflow and IRA. (ira.go.ke)
What documents do I need?
Common documents include the commercial invoice, packing list, Bill of Lading or Airway Bill, KRA PIN, freight details, cargo description and import declaration information.
Can an insurance agent help me obtain it?
Yes. A licensed agent or broker can obtain quotations and coordinate issuance through the underwriting insurer.
Can air cargo obtain marine insurance?
Yes. Marine cargo insurance can cover goods transported by air, sea, road, rail or a combination of methods.
When should I arrange the certificate?
Arrange it before the goods are exposed to uninsured transit and well before customs clearance.
What is the difference between Clause A and Clause C?
Clause A generally provides broader accidental physical-loss protection, subject to exclusions. Clause C covers a narrower list of specified major events.
Does the certificate cover theft?
Only where theft is included under the selected policy terms.
Can one certificate cover several shipments?
A single-shipment certificate ordinarily applies to the named consignment. Frequent importers can consider marine open cover, with declarations for individual shipments.
Does marine insurance cover delay?
Delay is commonly excluded, even where the delay follows physical damage.
What happens if the certificate details are incorrect?
Contact the insurer or intermediary immediately and request correction or endorsement before customs processing and before a claim arises.
Can Imana compare marine cargo quotations?
Yes. Imana can compare cargo clauses, premiums, excesses, extensions and claims terms from suitable insurers.
The Bottom Line
Getting a Digital Marine Cargo Insurance Certificate should begin before the goods arrive—not when the clearing agent is already trying to secure release.
A smooth process requires:
- Complete import documents
- Correct declaration information
- Accurate cargo value
- Clear cargo description
- Appropriate insurance clauses
- Payment through the approved process
- Electronic certificate verification
- Careful review of the issued certificate
Your cargo may travel thousands of kilometres through several ports, warehouses and vehicles. One accurate digital certificate can protect the value invested throughout that journey.
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call or WhatsApp: +254 796 209 402
Compare quotations. Insure before shipment. Verify the certificate. Let Imana handle the rest.
The Digital Marine Cargo Insurance procedure, customs requirements, portal workflows and payment arrangements may be updated by IRA, KRA or other relevant authorities. Cargo premiums, clauses, limits, excesses and exclusions depend on the selected insurer and shipment. Confirm the current official process and obtain a written policy before goods enter transit.