- Author: Raymond
- Category: Comprehensive Car Insurance in Kenya
- Category: Third Party Car Insurance in Kenya
Compare Motor Insurance Quotes in Kenya Before You Buy or Renew | Imana Insurance
Renewing your motor insurance in Kenya? Compare premiums, excesses, benefits and policy terms from different insurers before you pay. Get expert help from Imana Insurance.
Your Motor Insurance Is Expiring. Should You Just Renew It?
Your motor insurance renewal notice arrives.
The premium looks reasonable.
The insurer is familiar.
You have been insured with them for years.
So you pay.
Simple.
But before you renew your motor insurance in Kenya, there is one question worth asking:
Is this still the best insurance deal available for your vehicle?
Insurance companies regularly revise premiums, excesses, underwriting requirements, benefits and policy terms. Your vehicle value may also have changed.
A policy that made sense last year may not necessarily offer the best value this year.
This is why motorists should consider comparing motor insurance quotations before every renewal.
At Imana Insurance Agency Kenya Ltd, we help motorists compare quotations from different insurers, understand the differences and choose cover based on value — not simply the lowest premium.
Why You Should Compare Motor Insurance Quotes Before Renewal
Most motorists compare prices when buying a car.
They compare dealers.
They compare financing.
They compare fuel consumption.
They compare spare-parts prices.
Yet when insurance renewal comes around, many simply pay whatever appears on the renewal notice.
That can be expensive.
Motor insurance quotations can differ considerably from one insurer to another even when the vehicle, owner and insured value are exactly the same.
The differences may involve:
- Premium charged
- Basic excess
- Theft excess
- Young or inexperienced driver excess
- Excess protector
- Political Violence and Terrorism cover
- Windscreen limits
- Entertainment-system cover
- Courtesy car benefits
- Road rescue
- Geographical limits
- Claims procedures
- Approved repair arrangements
- Policy exclusions
A lower premium can sometimes come with higher excesses or fewer benefits.
That is why comparing insurance should go beyond asking:
“Who is cheapest?”
A better question is:
“Which policy gives me the best overall protection for the money I am paying?”
Don't Compare Premiums Alone
Suppose three insurers provide quotations for the same vehicle.
Insurer A
Premium: KSh 72,000
Insurer B
Premium: KSh 79,000
Insurer C
Premium: KSh 86,000
At first glance, Insurer A looks like the obvious choice.
But what happens when you look deeper?
Insurer A may have a higher compulsory excess.
Insurer B may include excess protector.
Insurer C may offer stronger windscreen limits, road rescue or broader additional benefits.
Suddenly the cheapest quotation is not automatically the best quotation.
This is where professional insurance advice matters.
1. Compare the Comprehensive Insurance Rate
Comprehensive motor insurance in Kenya is generally priced as a percentage of the insured value of the vehicle, subject to the insurer's minimum premium and underwriting requirements.
Different insurers may offer different rates for exactly the same vehicle.
The rate can be influenced by factors such as:
- Vehicle make and model
- Year of manufacture
- Vehicle value
- Usage
- Claims history
- Driver profile
- Type of vehicle
- Security features
- Underwriting experience with that vehicle category
A quotation should therefore be evaluated in its entirety rather than simply looking at the headline percentage.
2. Check the Basic Excess
This is one of the most overlooked parts of motor insurance.
The excess is the amount you may be required to contribute towards an insured claim before the insurer settles the remaining amount, subject to the policy terms.
Two insurers may charge similar premiums but apply very different excess conditions.
Before renewing, ask:
- What is my basic excess?
- Is it a percentage or fixed amount?
- Is there a minimum excess?
- Are there additional excesses?
- Does the policy include excess protector?
- Which excesses can and cannot be protected?
A difference of a few thousand shillings in premium may become insignificant if one policy exposes you to a much larger contribution during a claim.
3. Ask Whether Excess Protector Is Included
Excess Protector can protect the insured against certain applicable policy excesses, subject to the insurer's wording and conditions.
It is especially important to check whether it is:
- Included automatically
- Optional
- Charged separately
- Subject to limitations
Never assume your comprehensive motor insurance automatically includes every additional benefit.
Ask.
4. Check Political Violence and Terrorism Cover
Motorists sometimes assume comprehensive insurance covers every possible accidental or malicious event.
It does not.
Certain risks may require extensions.
One important extension is Political Violence and Terrorism, often referred to as PVT.
Depending on the policy wording, events connected to political unrest, civil disturbance, terrorism or related risks may require specific cover.
Before renewal, find out whether PVT is:
- Included
- Excluded
- Optional
- Available at an additional premium
The policy schedule should tell you what you actually purchased.
5. Compare Windscreen Limits
Modern windscreens can be expensive.
Some vehicles now have:
- Rain sensors
- Cameras
- Driver-assistance systems
- Heating elements
- Special tinting
- Heads-up display technology
Replacing such a windscreen may cost considerably more than expected.
When comparing comprehensive motor insurance quotes, check the windscreen limit.
A KSh 10,000 difference in annual premium may be less important than discovering after an accident that your windscreen benefit is insufficient.
6. Check Road Rescue and Towing Benefits
What happens when your car breaks down at night?
Or after an accident outside Nairobi?
Some comprehensive policies offer road-rescue services or towing assistance, while others have different limits and conditions.
Check whether the quotation includes:
- Towing
- Emergency roadside assistance
- Battery jump-start
- Tyre assistance
- Fuel assistance
- Accident recovery
- Geographical restrictions
This is especially useful for motorists who travel regularly outside major towns.
7. Compare Courtesy Car or Loss-of-Use Benefits
An accident can leave your vehicle in a garage for days or weeks.
But life does not stop.
You may still need to:
- Drive to work
- Take children to school
- Attend meetings
- Run your business
- Visit clients
Some insurers offer courtesy-car or related benefits under particular policies or extensions.
Check whether your quotation provides this benefit and what conditions apply.
8. Check the Insured Value of Your Vehicle
Motor insurance renewal is also an opportunity to review your vehicle's value.
Cars depreciate.
If your vehicle was insured at KSh 3 million last year, its current market value may be different.
Insuring a vehicle significantly above or below its realistic value can create complications.
A current valuation may therefore be required or advisable depending on the insurer and vehicle.
Ask your insurance adviser whether a new valuation is needed before renewal.
9. Compare Claims Support — Not Just Claims Promises
Insurance becomes real when there is a claim.
Before choosing an insurer, consider what happens after an accident.
Who will guide you?
Who follows up with the insurer?
Who helps you understand documents?
Who explains the excess?
Who communicates with the assessor?
Who helps follow up on repairs or settlement?
This is where an insurance intermediary can provide enormous value.
Buying insurance should not end when the certificate is issued.
The relationship should continue throughout the policy period and especially during claims.
10. Review Your Current Policy Before Buying Another One
If you already have motor insurance, your existing policy schedule is one of the most useful documents when shopping around.
It tells us:
- Your current insurer
- Vehicle details
- Current sum insured
- Existing benefits
- Current excesses
- Policy extensions
- Renewal date
Instead of starting blindly, an adviser can review your existing policy and determine whether alternative quotations offer genuine improvement.
What Does Imana Need to Compare Your Motor Insurance Quotes?
Getting a comparison does not need to be complicated.
For most private motor quotation requests, you can start with information such as:
- Vehicle registration number
- Make and model
- Year of manufacture
- Approximate/current vehicle value
- Intended use
- Existing insurer, where applicable
- Current insurance policy or renewal notice, where available
- Preferred additional benefits
Depending on the vehicle and insurer, further information may be requested.
Can You Compare Motor Insurance Quotes Online in Kenya?
Yes.
Motor insurance comparison has become increasingly digital.
You no longer necessarily need to physically visit several insurance companies and request separate quotations.
Through an insurance intermediary such as Imana Insurance Agency Kenya Ltd, you can submit your details remotely, receive quotation options, ask questions, make a decision and complete much of the insurance purchasing process digitally.
That means you can move from:
Request → Comparison → Advice → Purchase → Certificate
without spending an entire day moving from one insurer's office to another.
What Types of Motor Insurance Can You Compare?
Imana assists clients with different classes of motor insurance, including:
Private Motor Insurance
For privately owned vehicles used primarily for personal purposes.
Commercial Motor Insurance
For vehicles used in business and commercial activities.
PSV Taxi Insurance
For taxis and other qualifying public-service vehicles.
Matatu and Bus Insurance
For passenger-carrying commercial vehicles.
Motorcycle Insurance
Including private and commercial motorcycle risks.
Tuk-Tuk Insurance
For applicable commercial and PSV three-wheelers.
School Bus Insurance
For educational institutions operating student transport.
Tour Vehicle Insurance
For vehicles used by tour and travel operators.
Heavy Commercial Vehicle Insurance
For trucks and other commercial vehicles.
Third-Party or Comprehensive — Should You Compare Both?
Yes.
The cheapest insurance option is not necessarily comprehensive insurance.
Some motorists may choose Third-Party Only insurance depending on:
- Vehicle value
- Vehicle age
- Financial circumstances
- Risk appetite
- Usage
Others may require or prefer comprehensive insurance.
The important thing is understanding what each option does — and does not — cover.
An insurance adviser can help you decide which structure is suitable rather than automatically pushing you toward one product.
Why Use an Insurance Intermediary Instead of Approaching One Insurer?
When you approach one insurance company, that company can only offer you its own product.
That is perfectly normal.
But an intermediary can potentially look across several participating insurers and help you compare available options.
This creates an important difference.
The question changes from:
“What does this insurer sell?”
to:
“Which available insurer and policy structure makes the most sense for this particular client?”
That is the power of comparison.
What Imana Brings to the Comparison
Insurance comparison should not simply generate a list of prices.
The real value comes from interpreting those prices.
Imana combines four important elements:
Comparison
We help clients compare available quotations from different insurance companies.
Advice
We explain premiums, excesses, limits, extensions and other relevant policy terms so that the client can make an informed decision.
Digital Purchasing
Clients can request quotations and complete much of the purchase process remotely.
Human Insurance Expertise
When a client has questions — or a claim — there is still a human insurance professional involved.
Technology should make insurance easier.
It should not make insurance advice disappear.
The Cheapest Insurance Policy Can Become Expensive During a Claim
Imagine saving KSh 8,000 during renewal.
Sounds great.
Then an accident occurs.
You discover:
- Your excess is much higher
- A benefit you assumed was included is excluded
- Your windscreen limit is inadequate
- PVT was not included
- You did not purchase an important extension
That KSh 8,000 saving can suddenly look very small.
Price matters.
But value matters more.
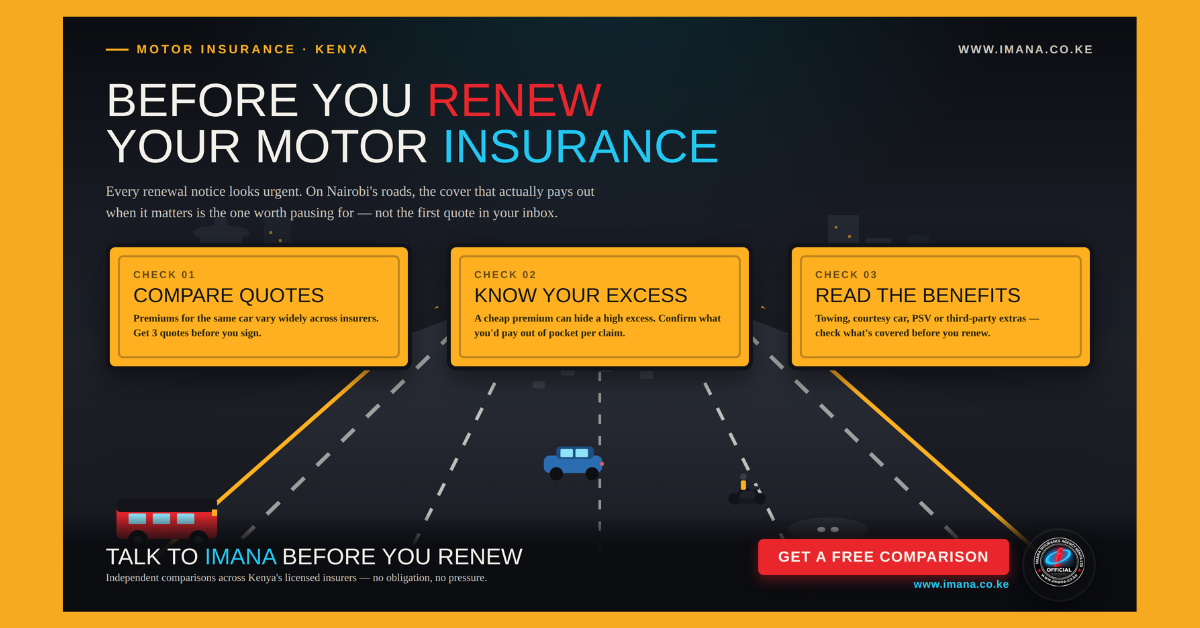
Questions to Ask Before Renewing Your Motor Insurance
Before paying your next renewal premium, ask:
- Is my vehicle insured at the correct value?
- Can I get a better quotation elsewhere?
- What excess applies?
- Is excess protector included?
- Is PVT included?
- What is my windscreen limit?
- Does the policy provide road rescue?
- Are there geographical restrictions?
- What important exclusions should I know about?
- Who will assist me if I have a claim?
If you cannot confidently answer these questions, don't rush the renewal.
Compare first.
Already Have a Renewal Notice? Send It to Imana
This is probably the easiest way to start.
If your motor insurance is about to expire, send Imana:
- Your current renewal notice or policy schedule
- Vehicle details
- Current vehicle value, where known
- Any additional benefits you want
Imana can then help you review the existing cover and explore alternative quotations where available.
You remain in control of the final decision.
Compare. Understand. Then Buy.
Motor insurance should not be a yearly ritual where you simply receive a figure and pay it.
Renewal is an opportunity to ask:
Am I paying the right premium?
Is my vehicle properly insured?
Are the benefits adequate?
What excess will I pay?
What exclusions apply?
Is there another insurer offering better value?
Those questions can save money.
But more importantly, they can prevent unpleasant surprises when a claim occurs.
Compare Motor Insurance Quotes with Imana Insurance
If your motor insurance is approaching renewal, don't automatically renew before comparing.
Imana Insurance Agency Kenya Ltd can help you compare available motor insurance quotations, understand the differences and choose cover based on your needs, budget and risk.
Start Your Motor Insurance Comparison
Motor Insurance:
https://imana.co.ke/insurance/motor-insurance
Request a Quote:
https://imana.co.ke/micro-quote
Website:
https://www.imana.co.ke
Call/WhatsApp:
+254 796 209 402
Imana Insurance Agency Kenya Ltd and MyKava Travel & Insurance
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Don't Just Renew. Compare First.
Compare. Understand. Buy with confidence.
Author: Raymond Momanyi - Founder and CEO Imana Insurance Agency Kenya Ltd (Unitas Digital Solutions)